
Personal Insurance
Business Insurance
- Business Insurance
- Industrial Special Risks (ISR) Insurance
- Commercial Property Owner Insurance
- Business Interruption Insurance
- Public Liability Insurance
- Professional Indemnity Insurance
- Management Liability Insurance
- Contract Works/Construction Insurance
- Marine Insurance
- Cyber Insurance
- Commercial Motor Insurance
- Faith & Not-for-Profit Organisations Insurance
Industry
- Retail and Consumer Insurance
- › Retail Strip Shop Insurance
- › Asian Grocery Store and Supermarket Insurance
- Hospitality and Tourism Insurance
- › Restaurant Insurance
- › Cafe and Bakery Insurance
- › Hotel and Hospitality Property Insurance
- › Takeaway Shop Insurance
- › Pub and Bar Insurance
- › Short Term Rental Insurance
- Commercial and Industrial Property Insurance
- › Warehouse Property Insurance
- › Service Station and Convenience Store Insurance
- › Loss of Rent Insurance
- › Shopping Centre Insurance
- › Rooming House Insurance
- Construction and Trades Insurance
- › Architect and Design Insurance
- › Plumber and Electrician Insurance
- Property and Real Estate Insurance
- › Property and Real Estate Agency Insurance
- Manufacturing and Industrial
- › Food Manufacturing Insurance
- Trade and Logistics Insurance
- Professional Services Insurance
- › Financial Services Insurance
- Health and Care Services Insurance
- › NDIS Provider Insurance
- › Aged Care Insurance
- › Psychologist Insurance
- › Physio Insurance
- Events and Entertainment Insurance
- › Personal Trainer and Gym Insurance
- Transport and Automotive Insurance
- › Rideshare Insurance
- › Truck Insurance
- Community, Education and Public Sector Insurance
- › Childcare Centre and Kindergarten Insurance
- High Value and Complex Business Insurance
- › Renewable Energy Insurance
- › Farm Insurance
Insurance by Industry
- Retail and Consumer Insurance
- › Retail Strip Shop Insurance
- › Asian Grocery Store and Supermarket Insurance
- Hospitality and Tourism Insurance
- › Restaurant Insurance
- › Cafe and Bakery Insurance
- › Hotel and Hospitality Property Insurance
- › Takeaway Shop Insurance
- › Pub and Bar Insurance
- › Short Term Rental Insurance
- Commercial and Industrial Property Insurance
- › Warehouse Property Insurance
- › Service Station and Convenience Store Insurance
- › Loss of Rent Insurance
- › Shopping Centre Insurance
- › Rooming House Insurance
- Construction and Trades Insurance
- › Architect and Design Insurance
- › Plumber and Electrician Insurance
- Property and Real Estate Insurance
- › Property and Real Estate Agency Insurance
- Manufacturing and Industrial
- › Food Manufacturing Insurance
- Trade and Logistics Insurance
- Professional Services Insurance
- › Financial Services Insurance
- Health and Care Services Insurance
- › NDIS Provider Insurance
- › Aged Care Insurance
- › Psychologist Insurance
- › Physio Insurance
- Events and Entertainment Insurance
- › Personal Trainer and Gym Insurance
- Transport and Automotive Insurance
- › Rideshare Insurance
- › Truck Insurance
- Community, Education and Public Sector Insurance
- › Childcare Centre and Kindergarten Insurance
- High Value and Complex Business Insurance
- › Renewable Energy Insurance
- › Farm Insurance
Insurance by Industry
Pub and Bar Insurance
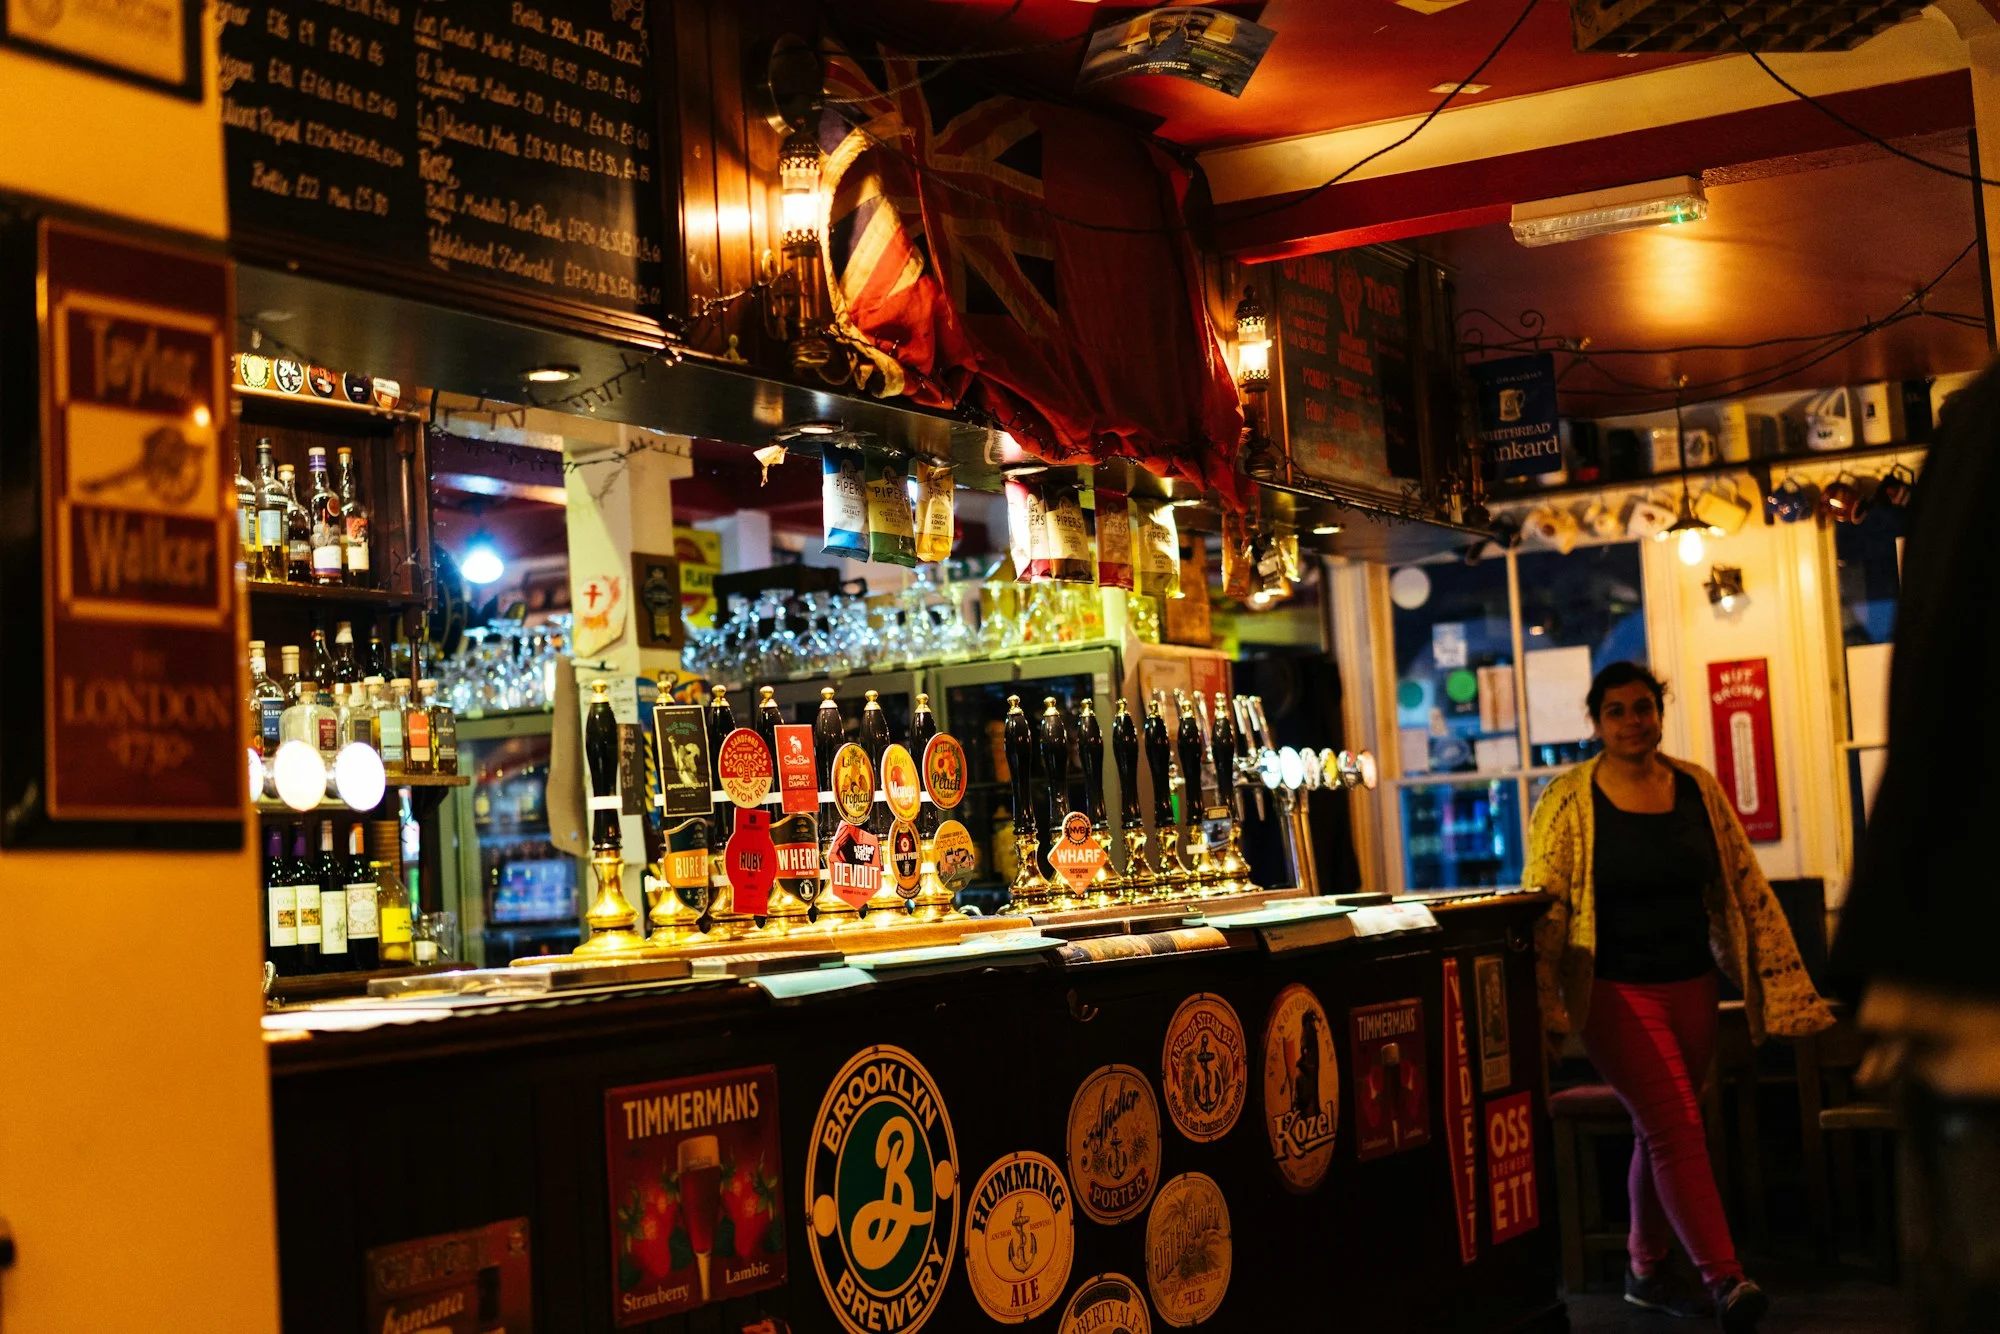
Bar insurance for pubs, small bars, wine bars, nightclubs and live music venues: patron injury, liquor liability, glass, cellar stock, gaming machines and lost trade.
Whether you run a corner pub with a gaming room or a laneway cocktail bar, bar insurance has to fit your licence and your crowd. Insurers will ask about crowd controllers, CCTV and live music, and the answers shape the liability terms, especially for assault claims. Fortis Risk Solutions compares wordings from insurers that write late-night venues and checks how each treats assault, glass breakage and spoiled cellar stock. When a landlord or promoter wants proof of cover, we send the certificate of currency. If a patron is hurt or the cool room fails, we help you lodge the claim. Have your liquor licence handy. Call 03 7046 3766 or send an enquiry.
What Pub and Bar Insurance Covers
Pub and bar insurance covers the venue fit-out, the cellar and bar stock, the gaming room and the liability that comes with serving alcohol, for pubs, small bars, wine bars, nightclubs and live music venues. Bar insurance is written around the licence: the trading hours, the crowd and whether food, entertainment or gaming is on offer.
Most claims start with a patron. Someone slips on a wet floor near the bar, falls on the stairs after a few drinks, or is hurt in a fight on the footpath outside. Broken glass cuts a customer or a staff member. A cellar cooling unit fails and the kegs and wine spoil. Gaming machines and the cash inside them attract break-ins.
Victorian liquor licences carry conditions such as trading hours and patron numbers, and responsible service of alcohol rules apply to licensees and bar staff. Landlords and event promoters ask for proof of public liability insurance before you trade. If a fire or flood shuts the venue, business interruption insurance can pay wages and rent while you rebuild.
Fortis Risk Solutions arranges pub insurance and nightclub insurance as part of our business insurance range from offices in Box Hill and Hawthorn. We look at the licence type, the closing time, the security arrangements and the entertainment before approaching insurers. A pub with accommodation upstairs often fits hotel insurance better. A venue built around its dining room may suit restaurant insurance.
Who this covers
Businesses in this group include:
- Pubs and hotel bars
- Bars and small bars
- Wine bars and cocktail bars
- Nightclubs and late-night venues
- Live music venues
If your business is not listed, ask us. The sections below are the starting point for any business in the group.
Pub and Bar Insurance: Cover Sections and Benefits
Related Client Case Studies
Cases from the Fortis Risk Solutions broking team. Client names have been removed.
Client case: Property Damage, Stock and Business Interruption After a Cyclone
The client situation: A restaurant located inside a shopping centre was forced to temporarily close after a cyclone in Queensland caused a prolonged power outage to the centre. The loss of electricity caused refrigerated and frozen food stock to spoil and prevented the restaurant from trading.
The incident happened just 6 weeks after the restaurant opened. We had provided holistic risk advice prior to the opening, and they had taken the necessary insurance to protect their operation.How the policy responded: Its Business Insurance policy included cover for Business Interruption arising from damage and loss of stock from storm damage affecting utility services, allowing the cyclone-related power outage and the resulting loss of income and gross profit to be recovered under the policy.
The restaurant claimed approximately $2,368 for spoiled stock and subsequently $1,384 a week of lost Gross Profit for 13 weeks until they fully recovered from the cyclone, a total indemnity of $23,989 including cleaning costs and other additional increased costs of working.How Fortis Risk Solutions helps: We advise on risk before a venue opens, not after the first loss. Utility failure and stock spoilage were on this policy because we raised them at the start.
Client case: Customer Slips on a Spill
The client situation: A bottle of cooking oil fell from a shelf and broke, leaving oil across the supermarket aisle. Before the area could be cleaned and secured, a customer slipped and suffered an injury. The customer made a compensation claim against the store.
How the policy could respond: Public Liability cover could respond to the third-party personal injury claim if the grocery store was legally liable, including covered legal defence costs and compensation.
How Fortis Risk Solutions helps: Slip claims can arrive months later. We tell clients what to record on the day, which helps the insurer defend the claim.
Every policy is different and the outcome of a claim depends on its terms. As your broker, Fortis Risk Solutions compares insurers and policy wording before you buy, and lodges and manages the claim for you when something happens. Talk to us about your own cover.
Pub and Bar Insurance FAQs
Public and products liability comes first, because landlords and promoters ask for a certificate of currency and because patron injury is the most common claim. Most venues then hold a business insurance package for the fit-out, stock and glass, with loss of trading on top. A licensed venue adds liquor liability. Workers compensation is separate and compulsory for most employers.
It depends on the wording. Some liability policies exclude assault and battery, while others cover it with a lower limit or attach conditions about security staff. Claims after a fight often allege that the venue served an intoxicated person or failed to manage the crowd. That makes the assault clause one of the first things to read in any bar policy.
Usually, yes. Late trading, larger crowds, dancing and outside promoters bring more injury and assault claims, and fewer insurers write venues that trade well past midnight. Expect questions on capacity, closing time, security, CCTV and incident records. A clean claims history and documented crowd control help when an insurer assesses the venue.
They can be, but they must be declared. Check who carries the risk of damage to the machines under your gaming arrangements, then insure on that basis. Cash in the machines, the gaming room safe and takings on the way to the bank fall under a money section with its own limits. Set those limits on your busiest weekend, not a quiet week.
Only if you add a spoilage or deterioration of stock section. Property cover pays to repair the cooling unit, not to replace the beer and wine it was protecting. Draught beer, wine and premium spirits can add up quickly, so the sum insured should reflect stock on hand before a big weekend or event rather than the midweek level.
Liquor and assault wordings vary widely between insurers, and the detail matters most after a late-night incident. As your broker, FRS helps you disclose the licence, hours and entertainment accurately, structure liability limits to meet lease and promoter requirements, compare insurers that write licensed venues and act as your advocate at claim time. Our hospitality insurance page covers the wider group, including cafes and caterers.
Bar insurance is judged on the night something goes wrong. The liability section matters most: confirm it covers a licensed venue, and look for any exclusion of injuries from fights or from the actions of security staff. Then check cellar stock, including spoilage when coolroom refrigeration fails. Gaming machines and the cash inside them may need to be listed separately. Each insurer words these sections differently, so it pays to read them together before you commit.
Talk to a broker about Pub and Bar Insurance
Call 03 7046 3766 on weekdays between 9:30am and 6pm, email admin@fortisrisksolutions.com.au, or send an enquiry and a broker from our Box Hill or Hawthorn office will come back to you about pub and bar insurance. Tell us what the business does and what the lease or contract asks for, and we take it from there.