
Personal Insurance
Business Insurance
- Business Insurance
- Industrial Special Risks (ISR) Insurance
- Commercial Property Owner Insurance
- Business Interruption Insurance
- Public Liability Insurance
- Professional Indemnity Insurance
- Management Liability Insurance
- Contract Works/Construction Insurance
- Marine Insurance
- Cyber Insurance
- Commercial Motor Insurance
- Faith & Not-for-Profit Organisations Insurance
Industry
- Retail and Consumer Insurance
- › Retail Strip Shop Insurance
- › Asian Grocery Store and Supermarket Insurance
- Hospitality and Tourism Insurance
- › Restaurant Insurance
- › Cafe and Bakery Insurance
- › Hotel and Hospitality Property Insurance
- › Takeaway Shop Insurance
- › Pub and Bar Insurance
- › Short Term Rental Insurance
- Commercial and Industrial Property Insurance
- › Warehouse Property Insurance
- › Service Station and Convenience Store Insurance
- › Loss of Rent Insurance
- › Shopping Centre Insurance
- › Rooming House Insurance
- Construction and Trades Insurance
- › Architect and Design Insurance
- › Plumber and Electrician Insurance
- Property and Real Estate Insurance
- › Property and Real Estate Agency Insurance
- Manufacturing and Industrial
- › Food Manufacturing Insurance
- Trade and Logistics Insurance
- Professional Services Insurance
- › Financial Services Insurance
- Health and Care Services Insurance
- › NDIS Provider Insurance
- › Aged Care Insurance
- › Psychologist Insurance
- › Physio Insurance
- Events and Entertainment Insurance
- › Personal Trainer and Gym Insurance
- Transport and Automotive Insurance
- › Rideshare Insurance
- › Truck Insurance
- Community, Education and Public Sector Insurance
- › Childcare Centre and Kindergarten Insurance
- High Value and Complex Business Insurance
- › Renewable Energy Insurance
- › Farm Insurance
Insurance by Industry
- Retail and Consumer Insurance
- › Retail Strip Shop Insurance
- › Asian Grocery Store and Supermarket Insurance
- Hospitality and Tourism Insurance
- › Restaurant Insurance
- › Cafe and Bakery Insurance
- › Hotel and Hospitality Property Insurance
- › Takeaway Shop Insurance
- › Pub and Bar Insurance
- › Short Term Rental Insurance
- Commercial and Industrial Property Insurance
- › Warehouse Property Insurance
- › Service Station and Convenience Store Insurance
- › Loss of Rent Insurance
- › Shopping Centre Insurance
- › Rooming House Insurance
- Construction and Trades Insurance
- › Architect and Design Insurance
- › Plumber and Electrician Insurance
- Property and Real Estate Insurance
- › Property and Real Estate Agency Insurance
- Manufacturing and Industrial
- › Food Manufacturing Insurance
- Trade and Logistics Insurance
- Professional Services Insurance
- › Financial Services Insurance
- Health and Care Services Insurance
- › NDIS Provider Insurance
- › Aged Care Insurance
- › Psychologist Insurance
- › Physio Insurance
- Events and Entertainment Insurance
- › Personal Trainer and Gym Insurance
- Transport and Automotive Insurance
- › Rideshare Insurance
- › Truck Insurance
- Community, Education and Public Sector Insurance
- › Childcare Centre and Kindergarten Insurance
- High Value and Complex Business Insurance
- › Renewable Energy Insurance
- › Farm Insurance
Insurance by Industry
Physio Insurance
Physio insurance for Melbourne physiotherapy clinics, sole practitioners and mobile physios: professional indemnity, public liability, treatment equipment, patient records and lost income.
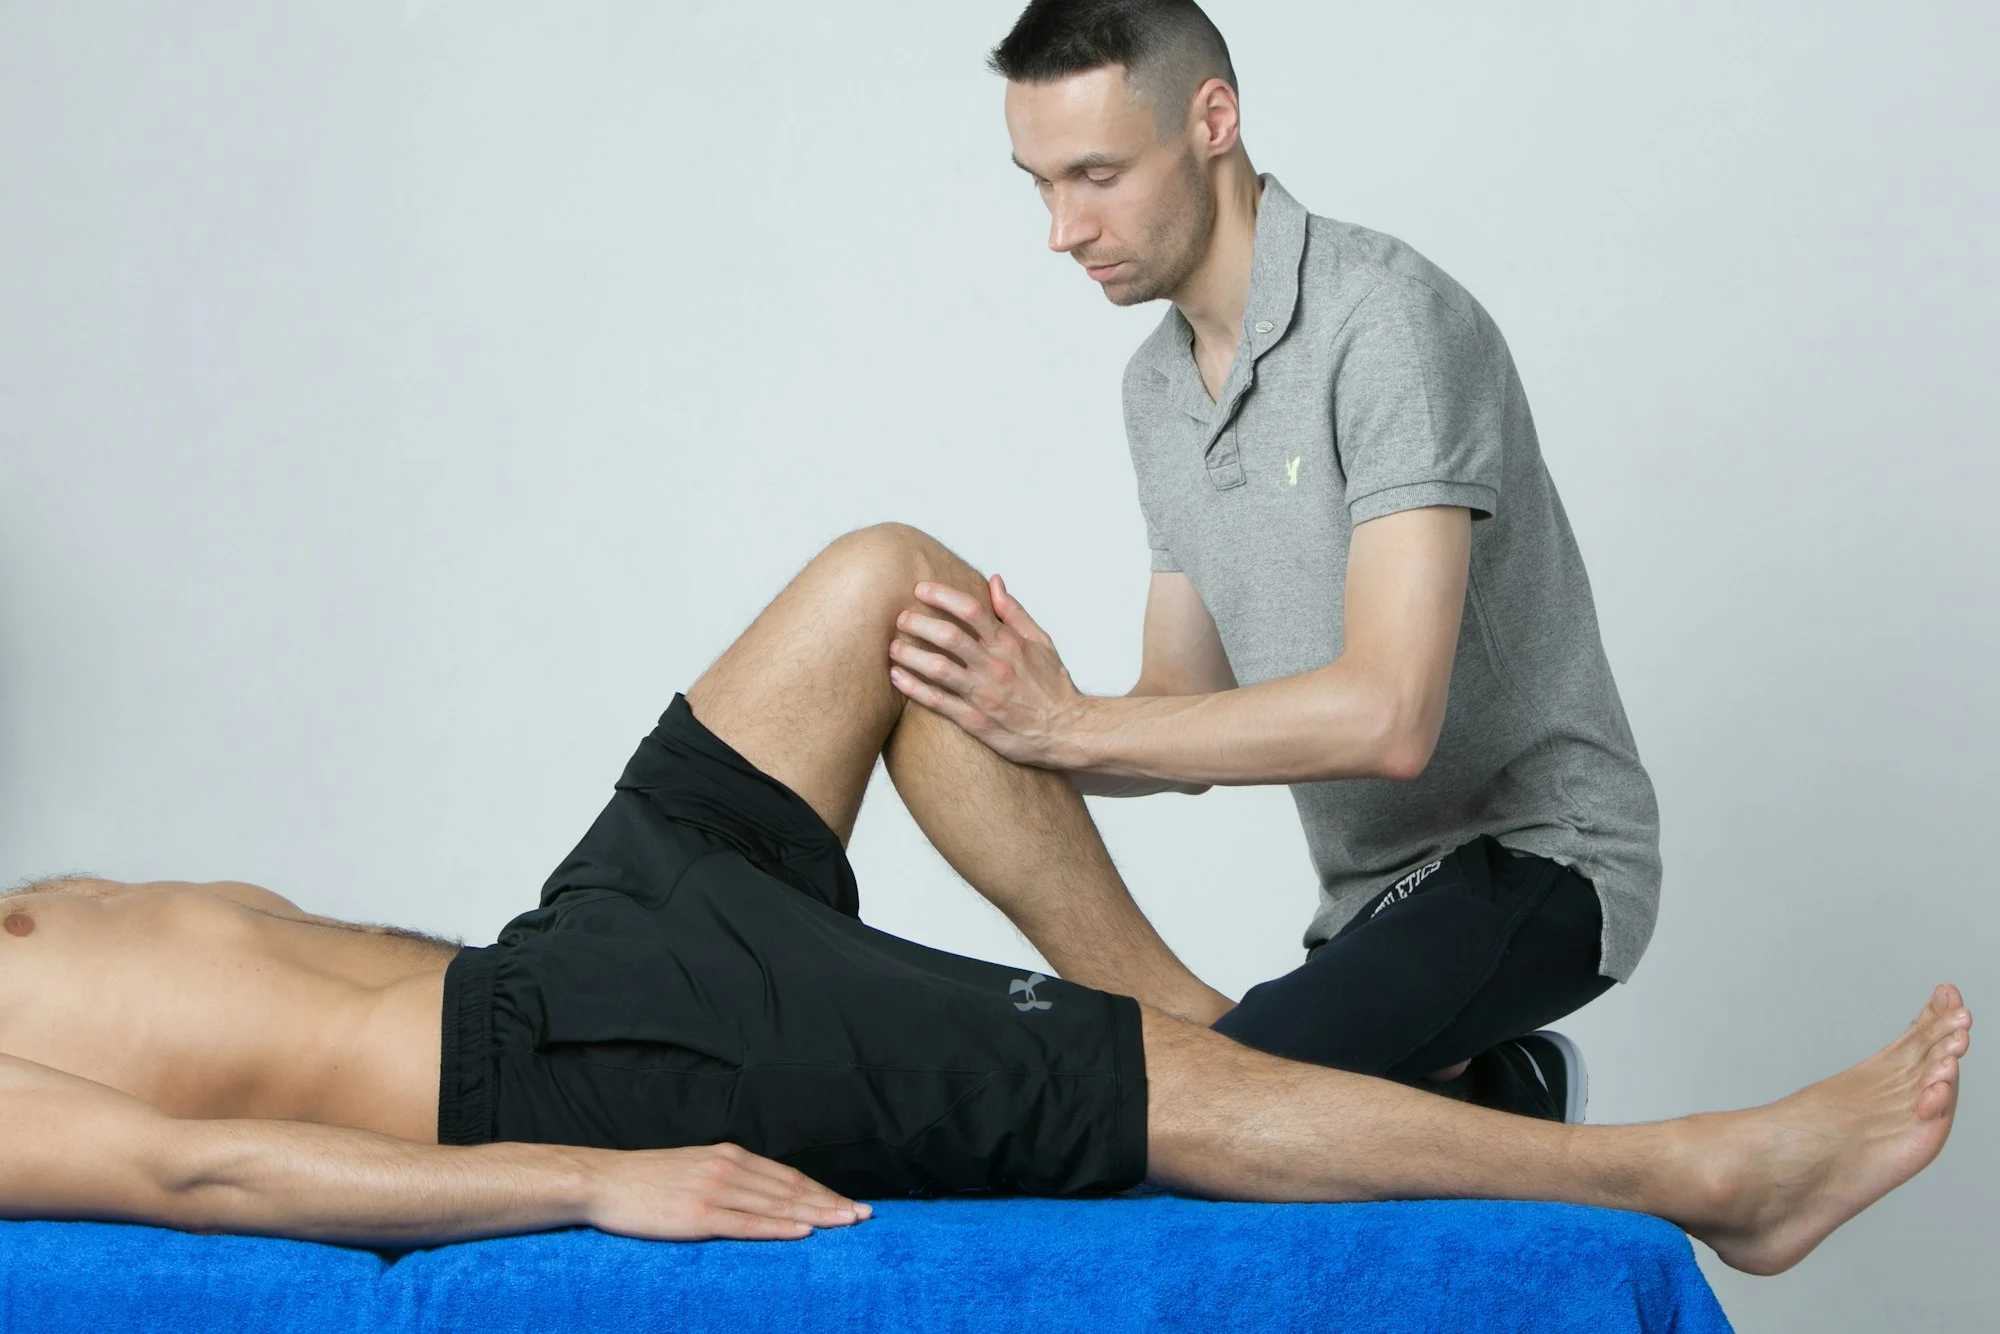
Physio insurance is for physiotherapists running their own practice, from a mobile physio working out of a car to a clinic with several treatment rooms and a rehab gym. At each AHPRA renewal you declare that your indemnity arrangements meet the board’s standard, and a clinic lease will usually ask for public liability as well. Fortis Risk Solutions compares PI wordings against the treatments you actually offer, such as dry needling, clinical Pilates and sports work, and checks how contractors working in your rooms are treated. If a patient complains or a claim arrives, we help you notify the insurer and manage the claim. List your services and staff, then call 03 7046 3766 or send an enquiry.
What Physio Insurance Covers
Physio insurance covers the professional indemnity, public liability, equipment and income risks of physiotherapists, physiotherapy clinics, exercise physiologists and mobile practitioners. It puts the policy your registration requires alongside the business cover a clinic needs, written around hands-on treatment. A sole practitioner visiting homes and a clinic with a rehab gym need different limits and different sections.
The claims follow the treatment. A patient says a manipulation or a dry needling session caused an injury. A client falls from a treatment table or off gym equipment during a class. A sports physio is blamed for clearing a player to return too early. A mobile physio's car is broken into, and the equipment and patient notes go with it.
Registered physiotherapists must meet the Physiotherapy Board of Australia registration standard for professional indemnity insurance arrangements, administered through AHPRA. Professional indemnity insurance answers that standard for work outside an employer's cover. Public liability insurance covers injury to patients and visitors that does not come from treatment, and most clinic leases ask for it.
Exercise physiologists are accredited through Exercise & Sports Science Australia rather than AHPRA, and schemes such as WorkSafe Victoria set their own insurance conditions for providers. Fortis Risk Solutions arranges physio insurance as part of our business insurance range from offices in Box Hill and Hawthorn. Larger multidisciplinary clinics often sit under medical practice insurance.
Who this covers
Businesses in this group include:
- Physiotherapy clinics
- Sole practitioner physios
- Exercise physiologists
- Sports physios
- Mobile physios
If your business is not listed, ask us. The sections below are the starting point for any business in the group.
Physio Insurance: Cover Sections and Benefits
Related Client Case Studies
Cases from the Fortis Risk Solutions broking team. Client names have been removed.
Client case: Stolen Laptop Creates a Data Breach
The client situation: An employee’s business laptop is stolen while travelling. The device contains locally stored client files and confidential information.
How the policy may respond: Cyber Insurance may assist with investigating whether information has been compromised, breach response, legal advice and required notifications, depending on the policy terms and security controls in place.
How Fortis Risk Solutions helps: Insurers ask about encryption and device security before they offer terms. We go through those questions with the client first, so the cover holds when it is needed.
Every policy is different and the outcome of a claim depends on its terms. As your broker, Fortis Risk Solutions compares insurers and policy wording before you buy, and lodges and manages the claim for you when something happens. Talk to us about your own cover.
Physio Insurance FAQs
Professional indemnity arrangements are. The Physiotherapy Board of Australia's registration standard requires registered physiotherapists to have appropriate professional indemnity insurance arrangements in place when they practise. Employer cover can meet the standard for employed work. Contractors, sole practitioners and clinic owners usually need their own policy. Public liability is not compulsory, though leases and sporting clubs commonly ask for it.
Professional indemnity and public liability are the base, usually on one combined policy. Add portable equipment cover if you treat in clients' homes, gyms or at sports grounds. Personal accident and illness cover matters because a sole practitioner generally has no workers compensation to fall back on. If your car carries equipment and patient files, tell your motor insurer. Contract work for a clinic does not bring you under the clinic's policy.
The clinic's policy covers the clinic. Contractor physios are not employees, so they need their own professional indemnity, and the clinic should sight a certificate of currency before they start. The clinic still needs its own liability cover and a business insurance package for fit-out, equipment and contents. Check how the contract allocates responsibility for patient claims.
It depends on the policy wording. Professional indemnity policies are written around a physiotherapist's scope of practice, and insurers may ask separately about dry needling, spinal manipulation, work with sports teams and travel with teams overseas. Declare each activity so the wording matches your practice. Ask before you add a new technique or a new club contract mid-term.
Most clinics hold patient records, booking systems and card payments online. The Privacy Act applies to health service providers regardless of turnover, and a data breach likely to cause serious harm must be reported to affected patients and the Information Commissioner. Mobile physios who keep notes on a phone carry the same duty. A cyber insurance policy can cover breach response, system restoration and some liability, depending on the policy wording.
Physio wordings differ on the treatments covered, retroactive dates, run-off and work with sports teams. As your broker, FRS helps you disclose your treatments and settings accurately, structure limits for your registration and contracts, compare insurers that specialise in health professions and act as your advocate at claim time. Clinics with rent and staff should add business interruption insurance so those costs are met while damaged rooms are repaired.
Talk to a broker about Physio Insurance
Call 03 7046 3766 on weekdays between 9:30am and 6pm, email admin@fortisrisksolutions.com.au, or send an enquiry and a broker from our Box Hill or Hawthorn office will come back to you about physio insurance. Tell us what the business does and what the lease or contract asks for, and we take it from there.