
Personal Insurance
Business Insurance
- Business Insurance
- Industrial Special Risks (ISR) Insurance
- Commercial Property Owner Insurance
- Business Interruption Insurance
- Public Liability Insurance
- Professional Indemnity Insurance
- Management Liability Insurance
- Contract Works/Construction Insurance
- Marine Insurance
- Cyber Insurance
- Commercial Motor Insurance
- Faith & Not-for-Profit Organisations Insurance
Industry
- Retail and Consumer Insurance
- › Retail Strip Shop Insurance
- › Asian Grocery Store and Supermarket Insurance
- Hospitality and Tourism Insurance
- › Restaurant Insurance
- › Cafe and Bakery Insurance
- › Hotel and Hospitality Property Insurance
- › Takeaway Shop Insurance
- › Pub and Bar Insurance
- › Short Term Rental Insurance
- Commercial and Industrial Property Insurance
- › Warehouse Property Insurance
- › Service Station and Convenience Store Insurance
- › Loss of Rent Insurance
- › Shopping Centre Insurance
- › Rooming House Insurance
- Construction and Trades Insurance
- › Architect and Design Insurance
- › Plumber and Electrician Insurance
- Property and Real Estate Insurance
- › Property and Real Estate Agency Insurance
- Manufacturing and Industrial
- › Food Manufacturing Insurance
- Trade and Logistics Insurance
- Professional Services Insurance
- › Financial Services Insurance
- Health and Care Services Insurance
- › NDIS Provider Insurance
- › Aged Care Insurance
- › Psychologist Insurance
- › Physio Insurance
- Events and Entertainment Insurance
- › Personal Trainer and Gym Insurance
- Transport and Automotive Insurance
- › Rideshare Insurance
- › Truck Insurance
- Community, Education and Public Sector Insurance
- › Childcare Centre and Kindergarten Insurance
- High Value and Complex Business Insurance
- › Renewable Energy Insurance
- › Farm Insurance
Insurance by Industry
- Retail and Consumer Insurance
- › Retail Strip Shop Insurance
- › Asian Grocery Store and Supermarket Insurance
- Hospitality and Tourism Insurance
- › Restaurant Insurance
- › Cafe and Bakery Insurance
- › Hotel and Hospitality Property Insurance
- › Takeaway Shop Insurance
- › Pub and Bar Insurance
- › Short Term Rental Insurance
- Commercial and Industrial Property Insurance
- › Warehouse Property Insurance
- › Service Station and Convenience Store Insurance
- › Loss of Rent Insurance
- › Shopping Centre Insurance
- › Rooming House Insurance
- Construction and Trades Insurance
- › Architect and Design Insurance
- › Plumber and Electrician Insurance
- Property and Real Estate Insurance
- › Property and Real Estate Agency Insurance
- Manufacturing and Industrial
- › Food Manufacturing Insurance
- Trade and Logistics Insurance
- Professional Services Insurance
- › Financial Services Insurance
- Health and Care Services Insurance
- › NDIS Provider Insurance
- › Aged Care Insurance
- › Psychologist Insurance
- › Physio Insurance
- Events and Entertainment Insurance
- › Personal Trainer and Gym Insurance
- Transport and Automotive Insurance
- › Rideshare Insurance
- › Truck Insurance
- Community, Education and Public Sector Insurance
- › Childcare Centre and Kindergarten Insurance
- High Value and Complex Business Insurance
- › Renewable Energy Insurance
- › Farm Insurance
Insurance by Industry
Personal Trainer and Gym Insurance
Gym insurance for gyms, personal trainers, yoga and pilates studios, martial arts schools and bootcamps: client injury, advice claims, equipment and lost income.
Gym insurance has to match how you train people. A studio owner carries the premises, the equipment and every member who walks in, while a mobile trainer mostly needs liability that follows them from one venue to the next. If you run a franchised gym, the franchise agreement usually sets the policies and limits you must hold. Fortis Risk Solutions compares wordings across insurers and checks the exclusions that catch fitness businesses out, such as hands-on adjustments, combat sports and supplements you sell. We send certificates to venues and councils when they ask, and help you lodge a claim if a client is hurt. Tell us what you teach and where. Call 03 7046 3766 or send an enquiry.
What Personal Trainer and Gym Insurance Covers
Personal trainer and gym insurance covers client injury, advice claims, equipment and lost income for gyms, fitness centres, personal trainers, studios and martial arts schools. A gym needs property and liability cover for the premises. A trainer who works across several venues needs liability and income cover that travels with them.
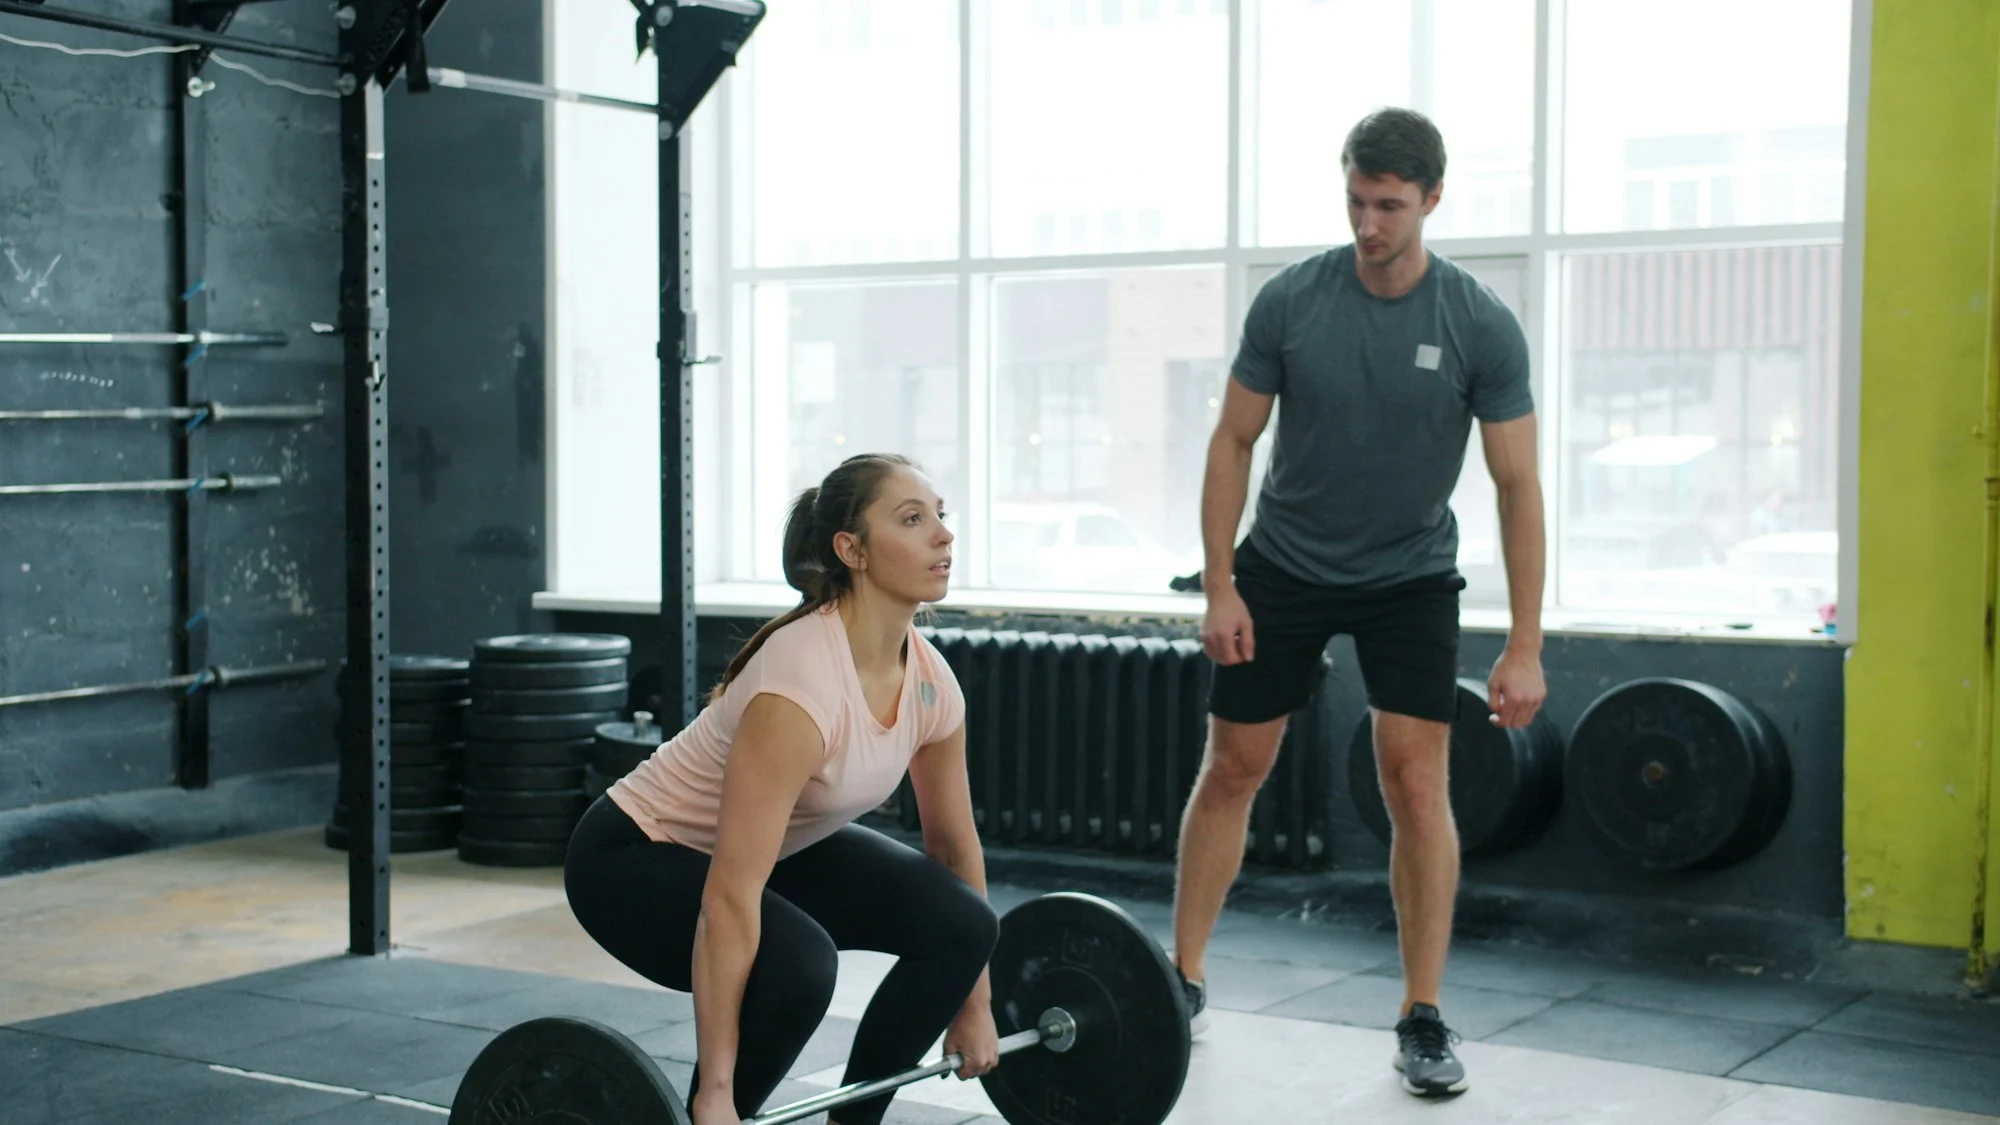
Most claims come from an exercise going wrong. A client tears a shoulder on a lift you programmed, drops a dumbbell on a foot, or comes off a treadmill. A yoga student is hurt during a hands-on adjustment. A bootcamp participant trips on uneven ground in a park. Equipment stolen from a car, or a break-in at a studio, stops income straight away.
Gyms, leisure centres and councils commonly ask fitness professionals for public liability insurance before they let them train clients on site or in parks. Many also ask for professional indemnity insurance, which answers claims that your instruction or program caused harm. A studio that leases its premises will be asked for a certificate of currency by the landlord as well.
Fortis Risk Solutions arranges gym insurance and personal trainer insurance as part of our business insurance range from offices in Box Hill and Hawthorn. We ask what you teach, where you train, how many clients you see and whether you sell supplements or nutrition plans before approaching insurers. Sole traders without sick leave should also look at personal accident and sickness insurance.
Who this covers
Businesses in this group include:
- Gyms and fitness centres
- Personal trainers, mobile and in-gym
- Group fitness instructors
- Yoga and pilates studios
- Martial arts schools
- Outdoor bootcamps
If your business is not listed, ask us. The sections below are the starting point for any business in the group.
Personal Trainer and Gym Insurance: Cover Sections and Benefits
Personal Trainer and Gym Insurance FAQs
Public liability and professional indemnity are the two that gyms and councils usually ask to see. Public liability answers claims for injury or property damage during a session. Professional indemnity answers claims that your advice or program caused harm. A sole trader without sick pay should add personal accident and sickness cover, because an injury to the trainer stops the income.
Yes. Fitness instructor insurance follows the person and covers liability and advice claims wherever you teach, including a community hall or a client's home. Gym insurance covers the business that runs a venue: contents, equipment and lost trading as well as liability. Gym owners usually hold it as a business insurance package. An instructor renting space in someone else's gym needs their own policy.
Usually, yes. Many Victorian councils require a permit for commercial fitness training in parks and reserves, and a certificate of currency for public liability is a normal condition of that permit. Check the limit your council asks for and whether it must be noted on the certificate. Outdoor sessions bring weather and uneven ground into the risk, so tell insurers where you train.
They can be, but they must be declared, and not every insurer writes them. Sparring, grappling and weapons training carry more injury risk than a group fitness class, so some policies exclude them or apply higher excesses. Declare every style you teach, including classes for children, because an undeclared activity is a common reason for a claim dispute.
No. A waiver can help show that a client understood the risks, but it may not stop a negligence claim under Australian law, and it does nothing for your equipment or your income. Use waivers and pre-exercise screening alongside insurance, not instead of it. One-off fitness events such as a charity run or a corporate challenge may need separate event insurance.
Fitness policies differ on the details that decide a claim: which activities are listed, whether nutrition advice is included and how equipment left in a car is treated. As your broker, FRS helps you disclose every class and service accurately, structure liability limits to match gym and council requirements, compare insurers that write fitness risks and act as your advocate at claim time. Gym owners should also review business interruption insurance for time closed after damage.
Talk to a broker about Personal Trainer and Gym Insurance
Call 03 7046 3766 on weekdays between 9:30am and 6pm, email admin@fortisrisksolutions.com.au, or send an enquiry and a broker from our Box Hill or Hawthorn office will come back to you about personal trainer and gym insurance. Tell us what the business does and what the lease or contract asks for, and we take it from there.