
Personal Insurance
Business Insurance
- Business Insurance
- Industrial Special Risks (ISR) Insurance
- Commercial Property Owner Insurance
- Business Interruption Insurance
- Public Liability Insurance
- Product Liability Insurance
- Professional Indemnity Insurance
- Management Liability Insurance
- Contract Works/Construction Insurance
- Marine Insurance
- Cyber Insurance
- Commercial Motor Insurance
- Faith & Not-for-Profit Organisations Insurance
Industry
- Retail and Consumer Insurance
- › Retail Strip Shop Insurance
- › Asian Grocery Store and Supermarket Insurance
- › Bottle Shop Insurance
- Hospitality and Tourism Insurance
- › Restaurant Insurance
- › Cafe and Bakery Insurance
- › Hotel and Hospitality Property Insurance
- › Takeaway Shop Insurance
- › Pub and Bar Insurance
- › Catering Insurance
- Commercial and Industrial Property Insurance
- › Warehouse Property Insurance
- › Service Station and Convenience Store Insurance
- › Loss of Rent Insurance
- › Shopping Centre Insurance
- › Rooming House Insurance
- › Childcare Property Insurance
- Construction and Trades Insurance
- › Architect and Design Insurance
- › Electrician Insurance
- › Plumbers Insurance
- › Solar Installer Insurance
- › Tradie Insurance
- Property and Real Estate Insurance
- › Property and Real Estate Agency Insurance
- Manufacturing and Industrial
- › Food Manufacturing Insurance
- Trade and Logistics Insurance
- Professional Services Insurance
- › Financial Services Insurance
- Health and Care Services Insurance
- › NDIS Provider Insurance
- › Aged Care Insurance
- › Psychologist Insurance
- › Physio Insurance
- › Counsellor Insurance
- Events and Entertainment Insurance
- › Gym and Fitness Studio Insurance
- › Personal Trainer Insurance
- Transport and Automotive Insurance
- › Truck Insurance
- › Mechanic Insurance
- Community, Education and Public Sector Insurance
- › Childcare Centre and Kindergarten Insurance
- High Value and Complex Business Insurance
- › Renewable Energy Insurance
- › Farm Insurance
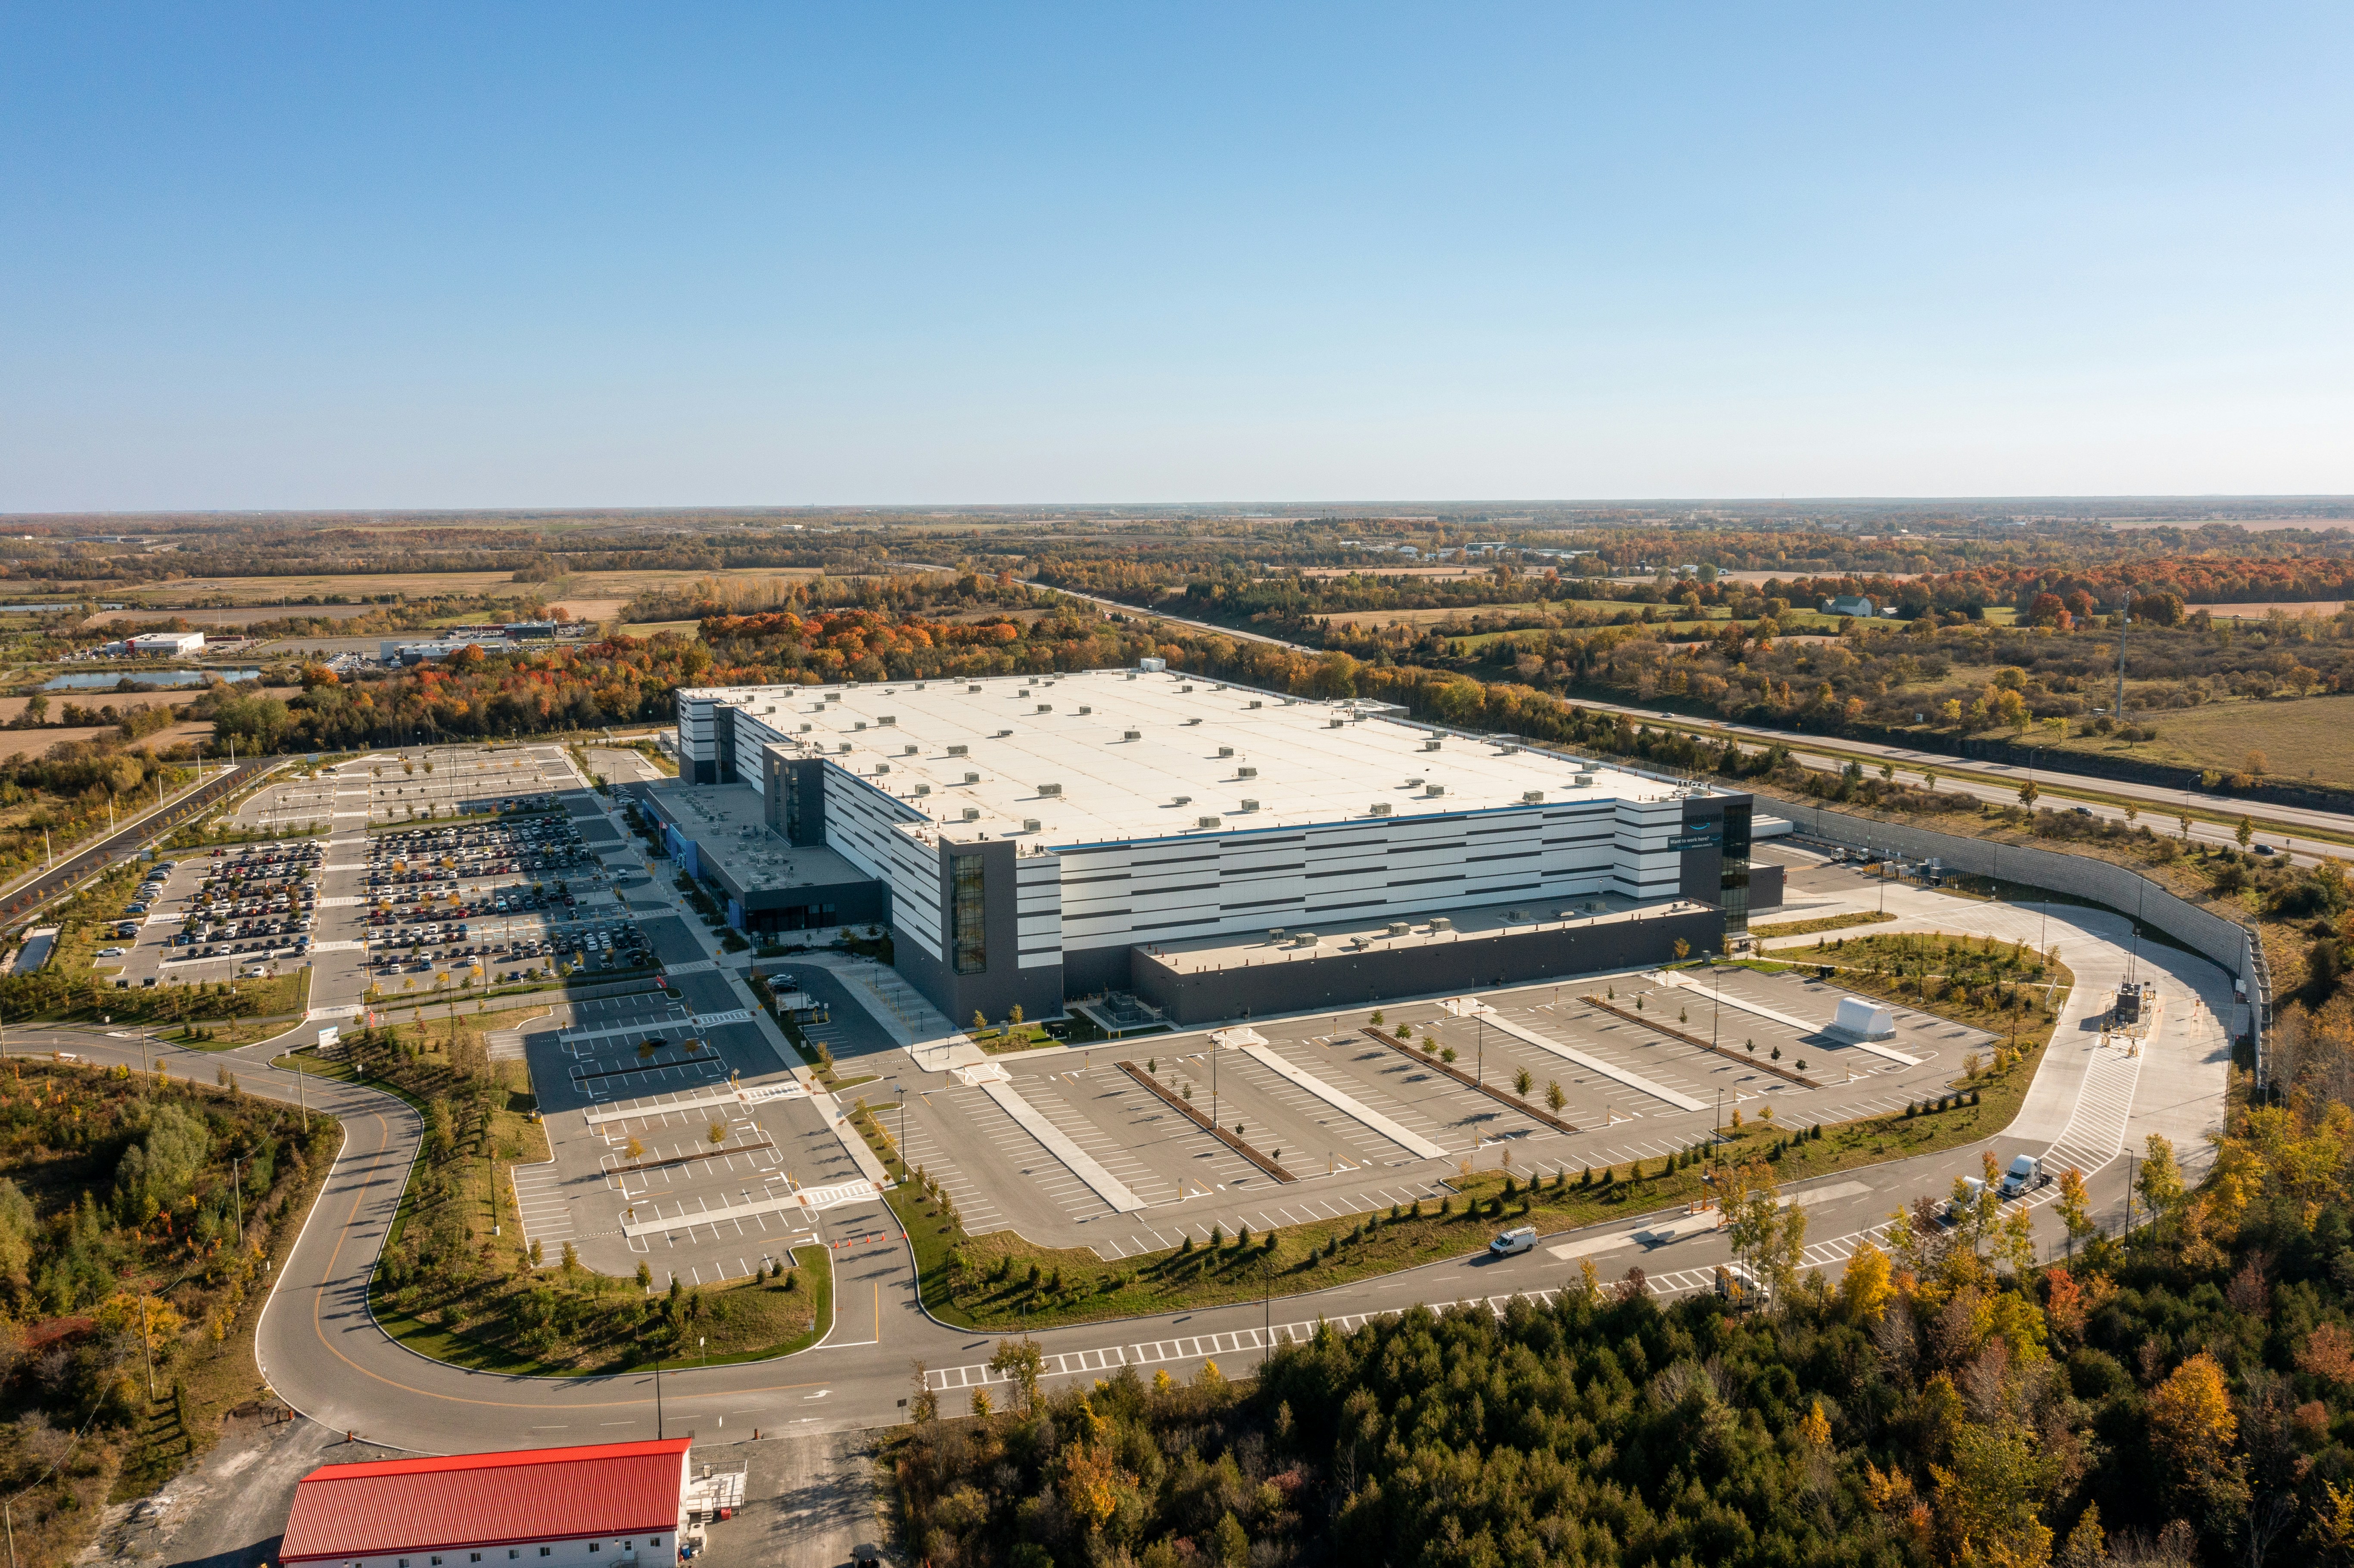
Business Insurance
Commercial Property Owner Insurance
Commercial property insurance for the building, the rental income it earns and the legal liabilities that come with owning it.
Commercial property insurance is for people who own an office, shop, factory or warehouse, whether they trade from it or lease it out. Your lender will usually want the building insured with its interest noted, and each lease can shift some insurance duties onto you or the tenant. Fortis Risk Solutions compares owner wordings across insurers and checks the sum insured against today’s rebuild cost, including demolition and professional fees. We also look at the loss of rent period and at the vacancy clause, which can restrict cover once a building has been empty for longer than the policy allows. Send us the address and copies of the current leases. Call 03 7046 3766 or send an enquiry.
What Commercial Property Insurance Covers
Commercial property insurance, also called commercial property owners insurance, covers the building, lost rent and owner's liability, whether the premises are owner-occupied or leased to tenants.
It protects the building, the rental income and the legal liabilities of ownership. Residential investment properties fall under landlord insurance instead. Buildings inside a strata-titled complex are covered by strata insurance. It sits within our business insurance range at Fortis Risk Solutions.
Commercial Property Owner Insurance: Cover Sections and Benefits
What Commercial Property Owner Insurance does not cover
The policy follows the building and the owner’s liability, not the tenant’s business. That line causes most of the surprises at claim time. Typical exclusions under commercial property insurance:
- The tenant’s stock, fit-out and equipment, which the tenant insures
- Wear and tear, defective building work and rot found once repairs begin
- Loss of rent where no loss of rent or interruption section was taken
- Damage from a tenant process the insurer was never told about, such as commercial cooking or spraying
- Common property in a strata scheme, insured instead by the owners corporation under strata cover
- Buildings left unoccupied beyond the period allowed after a tenant moves out
- Gradual water damage from failed waterproofing or blocked gutters
FRS checks the lease, the permitted use and who insures what before placing the policy, so the wording lines up with the tenancy schedule.
How Commercial Property Owner Insurance premiums are set
Underwriters price the building and the trade going on inside it. An office block and a strip of food tenancies at the same value are not the same risk. The main factors behind commercial property insurance:
- Sum insured for the building, including removal of debris and professional fees
- Construction and age, with older wiring, timber framing and combustible cladding rated harder
- Tenant activities, since kitchens, workshops and chemical storage lift the fire load
- Fire protection and security, including sprinklers, hydrants, alarms, lighting and fencing
- Location and natural hazard exposure, particularly flood and bushfire
- Occupancy, and how long any tenancy has sat vacant
- The excess accepted, and whether loss of rent is insured and for how long
Keep the sum insured current. FRS reviews replacement values at every renewal and can arrange a valuation, since underinsurance remains the most common problem we find on commercial buildings.
How to claim on Commercial Property Owner Insurance
Owners often hear about damage second hand, from a tenant or a property manager, which costs days. Call us at the first report rather than after the repair quote arrives. The FRS process:
- Notify: Call FRS as soon as the damage is reported to you, even when the tenant found it
- Make safe: Make the building safe and arrange emergency repairs to stop further loss, keeping the invoices
- Report: Report break-ins, vandalism or arson to police and record the report number
- Do not admit liability: Do not admit liability to a tenant or visitor who says the building caused their loss
- Send the evidence: Send us photos, the lease, repair quotes and the rent record if income is affected
- We lodge and manage: FRS lodges the claim, manages the assessor and follows the repair through to settlement
The steps and contacts are set out on our make a claim page.
Commercial Property Owner Insurance compared with Landlord Insurance
| Question | Commercial property owner | Residential landlord |
|---|---|---|
| What it covers | Commercial building, owner’s liability, loss of rent and often glass | House or unit, contents you supply, tenant damage and rent default |
| Who buys it | Owners of shops, offices, factories and mixed use buildings | Owners of houses, units and apartments let to tenants |
| Typical trigger | Fire, storm, impact, water damage or a claim by someone injured at the property | Storm or fire damage, malicious damage by a tenant, or unpaid rent |
| Sits with | Business insurance held by the tenant | Home and contents cover on the owner’s own residence |
Mixed use buildings need care, because a shop downstairs and flats upstairs can fall between the two wordings. FRS places the whole building on one policy where possible, or arranges landlord cover alongside it where the residential part is better insured separately.
Commercial Property Owner Insurance - Client Case Studies
Cases from the Fortis Risk Solutions broking team. Client names have been removed.
Client case: Success Story: Break-in Causes Building Damage
The client situation: Thieves broke into a warehouse property in Queensland owned by our client overnight, forcing open the motorised sliding gate at the front of the property and damaging the roller door, locks, security fixtures and sections of the main warehouse building. The thieves stole a whole van of white goods belonging to the tenant who leased the warehouse.
How we handled the case: We helped our client, as the warehouse property owner, lodge a claim through their Commercial Property Owner (CPO) Insurance for the insured damage to the building and landlord-owned fixtures caused during the break-in. The insurance covered the cost of repairing the sliding gate and motor at the front of the warehouse, as well as the roller door, at a total cost of $24,598.
The tenant also reported that stock had been stolen from inside the warehouse. The tenant would generally need its own insurance for stolen tenant-owned stock and contents. If covered building damage made the warehouse temporarily unusable and resulted in lost rent, applicable Loss of Rent cover could also respond.Worth knowing: It is important for a commercial property owner and a tenant to understand that the landlord’s insurance and the tenant’s insurance for the same warehouse do not overlap. The commercial property owner policy covers the building, fixtures and landlord liability, while the tenant’s policy typically covers the tenant’s business stock and operational liability.
How Fortis Risk Solutions helps: We explain to owners and tenants where one policy ends and the other begins, before a loss shows up the gap.
Every policy is different and the outcome of a claim depends on its terms. As your broker, Fortis Risk Solutions compares insurers and policy wording before you buy, and lodges and manages the claim for you when something happens. Talk to us about your own cover.
Commercial Property Owner Insurance FAQs
Buildings should be insured for full replacement cost, not market value. Underinsurance can cut a claim payout sharply. We give clients valuation guidance and review sums insured regularly, so the figure keeps pace with building costs.
It depends on the lease. Landlords usually insure the building and the liabilities that come with owning it, including property owner's public liability insurance. Tenants insure their own contents, fit-out and business activities. We read the lease and check the split is right.
Yes, though vacancy changes the cover. Unoccupied buildings often attract special terms, higher excesses or extra risk controls. We arrange suitable cover, handle the vacancy disclosure and check how business interruption insurance responds while the space is empty.
Building values, lease obligations and liability limits sit in different documents, and a gap between them only shows up at claim time. As your broker, FRS helps you disclose the property and its use accurately, set sums insured and limits that match, compare specialist property insurers and act as your advocate when you claim.
For a building you lease out, start with the sum insured. It should reflect the cost to rebuild today, including demolition and professional fees, which is rarely the price you paid. Loss of rent is the second test: how many months it pays while repairs run. Finally, read the vacancy clause, because cover can be restricted once the property sits empty beyond a set period. A broker compares these clauses across insurers before you renew.
Related reading
Related pages
Related industry pages: Loss of Rent Insurance, Service Station and Convenience Store Insurance, Hotel and Hospitality Property Insurance, Childcare Centre and Kindergarten Insurance, Commercial and Industrial Property Insurance
Talk to a broker about Commercial Property Owner Insurance
Call 03 7046 3766 on weekdays between 9:30am and 6pm, email admin@fortisrisksolutions.com.au, or send an enquiry and a broker from our Box Hill or Hawthorn office will come back to you about commercial property owner insurance. Tell us what the business does and what the lease or contract asks for, and we take it from there.