Personal Insurance
Business Insurance
- Business Insurance
- Industrial Special Risk (ISR) Insurance
- Commercial Property Owner Insurance
- Business Interruption Insurance
- Public Liability Insurance
- Professional Indemnity Insurance
- Management Liability Insurance
- Contract Works/Construction Insurance
- Marine Insurance
- Cyber Insurance
- Commercial Motor Insurance
- Faith & Not-for-Profit Organisations Insurance
Industry Insurance
Business Insurance
Commercial Motor Insurance
Commercial motor insurance for work vehicles and fleets, covering accident damage, theft and third-party liability.
What Commercial Motor Insurance Covers
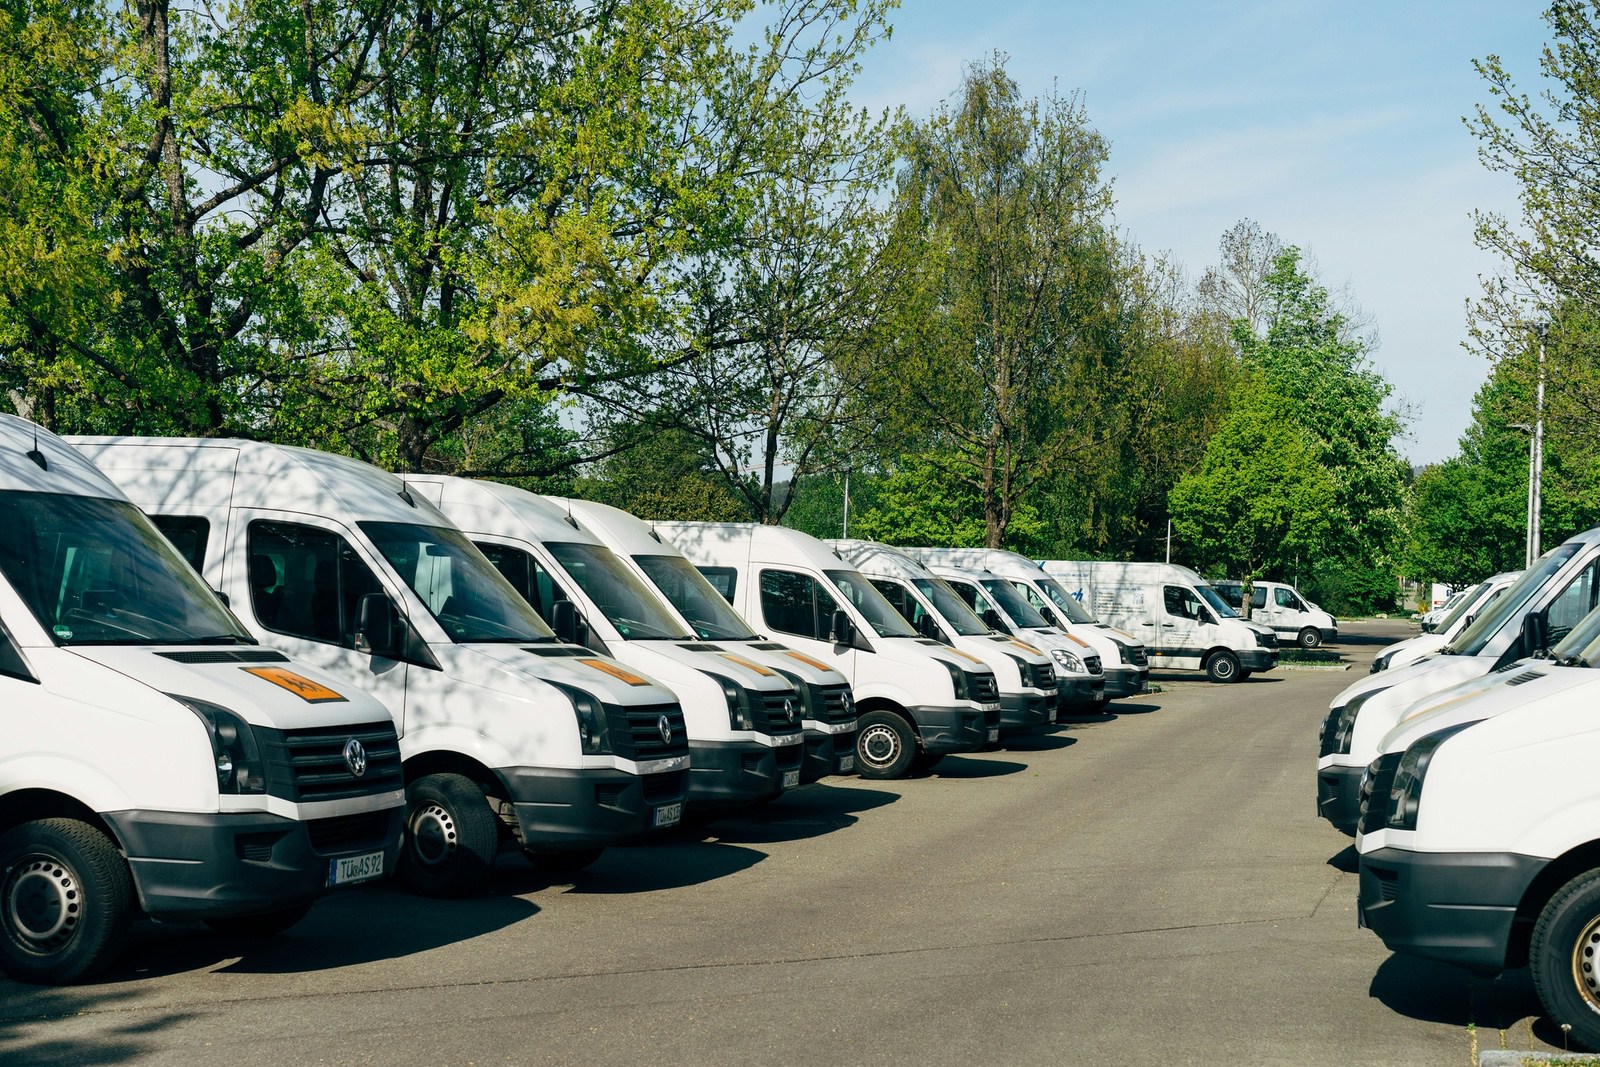
Commercial motor insurance covers businesses against financial loss from accidents, theft and liability involving vehicles used for work.
It pays for damage to insured vehicles, third-party property damage, theft, fire and legal liability. That covers the everyday risks of running cars, vans, utilities, trucks and commercial fleets.
From a single work ute to a large fleet, commercial motor insurance is a core protection for Australian businesses that rely on vehicles to deliver goods and services. Most operators hold it as part of a broader business insurance program. It sits within our business insurance range at Fortis Risk Solutions.
Commercial Motor Insurance: Cover Sections and Benefits
What Commercial Motor Insurance does not cover
Commercial motor insurance covers the vehicle and the damage it does to others. It does not cover the way the vehicle wears out, and it will not respond if the vehicle was being used outside what was declared. Common exclusions are:
- Drivers who are unlicensed, disqualified, or outside the driver criteria shown on the schedule
- Driving under the influence of alcohol or drugs, and refusing a breath or blood test
- Use the policy was not rated for, such as carrying passengers for hire or towing beyond the rated capacity
- Mechanical, electrical or electronic breakdown, wear and tear, rust and gradual deterioration
- Damage to tyres from braking, punctures or road contact, unless part of a wider accident
- Goods and tools carried in or on the vehicle, which need a transit or tools of trade section
- Injury to your own employees, which belongs with workers compensation
Workers compensation is compulsory for employers in Victoria, and it sits outside the motor policy. FRS checks driver criteria and declared use against how the fleet is really run before cover is bound.
How Commercial Motor Insurance premiums are set
Underwriters price commercial motor insurance on the vehicle, the driver and the job the vehicle does. Turnover has almost nothing to do with it. What matters is:
- Vehicle type, weight and value, and whether it carries signage or specialised body work
- Declared use: own goods, hire and reward, courier work, or passenger carrying
- Radius of operation, from suburban delivery to interstate line haul
- Driver age, experience and traffic history, and whether cover is for listed drivers or any driver
- Where the vehicle is kept overnight, plus immobilisers, dash cameras and telematics
- Claims history across the fleet, including small at fault knocks
- Agreed or market value, the basic excess, and any age or inexperience excess
Fleets are often rated on the whole book rather than car by car, which rewards steady claims performance. FRS presents the fleet history properly so a bad year is explained rather than simply loaded.
How to claim on Commercial Motor Insurance
Vehicles are the claim most businesses make first, and the first hour at the roadside decides how smooth the rest of it is. Give drivers a card with the FRS number in every vehicle. The process:
- Make the scene safe, check for injuries and call emergency services if anyone is hurt
- Exchange names, licence details, registration and insurer details with the other driver, and photograph both vehicles and the road position
- Report theft, attempted theft or malicious damage to police and keep the reference number
- Do not admit liability at the scene and do not agree to pay anything, whatever the other party says
- Call FRS the same day, and do not authorise repairs before the insurer or assessor has approved them
- FRS lodges the claim, arranges the assessment and any hire vehicle, then handles recovery against the other driver
Start at our make a claim page.
Commercial Motor Insurance compared with Private Motor Insurance
| Question | Commercial Motor | Private Motor |
|---|---|---|
| What it covers | Vehicles used for work, including utes, vans, trucks and trailers | A family car used for social, domestic and commuting purposes |
| Who buys it | Trades, transport operators, couriers and any business running vehicles | Private owners with no business use of the car |
| Typical trigger | An at fault accident on a job, theft of a loaded ute, damage to a hired trailer | A weekend accident, a hailstorm, theft from the driveway |
| Sits with | Public liability, tools of trade, goods in transit | Home and contents |
The line matters at claim time. A private policy can be declined where the car was being used for deliveries, so once a vehicle carries stock, tools or paying passengers it belongs on commercial motor insurance and on the wider business insurance programme rather than a personal policy.
Commercial Motor Insurance FAQs
Commercial motor insurance is written for vehicles used mainly for business, including carrying tools, goods or passengers for work. A personal policy may not respond to business use, particularly for trades, deliveries or multiple drivers. Privately owned prestige vehicles belong under prestige motor insurance.
Yes. The policy can be structured for named drivers or as an open driver policy, subject to age and licence conditions.
Some policies give limited cover for tools and accessories. Higher values are usually insured under a General Property or Tools policy.
Yes. Businesses running several vehicles can move to a fleet policy, which simplifies administration, keeps cover consistent and may reduce the total premium.
Commercial motor policies differ in driver conditions, vehicle use definitions, claims handling and exclusions. As your broker, FRS helps you:
- Define business use and driver profiles correctly
- Structure excesses and cover options
- Assess whether a fleet or individual policies suit you better
- Coordinate claims and keep downtime short
- Confirm vehicles, accessories and modifications are adequately insured
Builders should check how the policy lines up with their contract works insurance, and operators carrying customers' goods should check where marine insurance takes over.