
Personal Insurance
Business Insurance
- Business Insurance
- Industrial Special Risks (ISR) Insurance
- Commercial Property Owner Insurance
- Business Interruption Insurance
- Public Liability Insurance
- Professional Indemnity Insurance
- Management Liability Insurance
- Contract Works/Construction Insurance
- Marine Insurance
- Cyber Insurance
- Commercial Motor Insurance
- Faith & Not-for-Profit Organisations Insurance
Industry
- Retail and Consumer Insurance
- › Retail Strip Shop Insurance
- › Asian Grocery Store and Supermarket Insurance
- Hospitality and Tourism Insurance
- › Restaurant Insurance
- › Cafe and Bakery Insurance
- › Hotel and Hospitality Property Insurance
- › Takeaway Shop Insurance
- › Pub and Bar Insurance
- › Short Term Rental Insurance
- Commercial and Industrial Property Insurance
- › Warehouse Property Insurance
- › Service Station and Convenience Store Insurance
- › Loss of Rent Insurance
- › Shopping Centre Insurance
- › Rooming House Insurance
- Construction and Trades Insurance
- › Architect and Design Insurance
- › Plumber and Electrician Insurance
- Property and Real Estate Insurance
- › Property and Real Estate Agency Insurance
- Manufacturing and Industrial
- › Food Manufacturing Insurance
- Trade and Logistics Insurance
- Professional Services Insurance
- › Financial Services Insurance
- Health and Care Services Insurance
- › NDIS Provider Insurance
- › Aged Care Insurance
- › Psychologist Insurance
- › Physio Insurance
- Events and Entertainment Insurance
- › Personal Trainer and Gym Insurance
- Transport and Automotive Insurance
- › Rideshare Insurance
- › Truck Insurance
- Community, Education and Public Sector Insurance
- › Childcare Centre and Kindergarten Insurance
- High Value and Complex Business Insurance
- › Renewable Energy Insurance
- › Farm Insurance
Insurance by Industry
- Retail and Consumer Insurance
- › Retail Strip Shop Insurance
- › Asian Grocery Store and Supermarket Insurance
- Hospitality and Tourism Insurance
- › Restaurant Insurance
- › Cafe and Bakery Insurance
- › Hotel and Hospitality Property Insurance
- › Takeaway Shop Insurance
- › Pub and Bar Insurance
- › Short Term Rental Insurance
- Commercial and Industrial Property Insurance
- › Warehouse Property Insurance
- › Service Station and Convenience Store Insurance
- › Loss of Rent Insurance
- › Shopping Centre Insurance
- › Rooming House Insurance
- Construction and Trades Insurance
- › Architect and Design Insurance
- › Plumber and Electrician Insurance
- Property and Real Estate Insurance
- › Property and Real Estate Agency Insurance
- Manufacturing and Industrial
- › Food Manufacturing Insurance
- Trade and Logistics Insurance
- Professional Services Insurance
- › Financial Services Insurance
- Health and Care Services Insurance
- › NDIS Provider Insurance
- › Aged Care Insurance
- › Psychologist Insurance
- › Physio Insurance
- Events and Entertainment Insurance
- › Personal Trainer and Gym Insurance
- Transport and Automotive Insurance
- › Rideshare Insurance
- › Truck Insurance
- Community, Education and Public Sector Insurance
- › Childcare Centre and Kindergarten Insurance
- High Value and Complex Business Insurance
- › Renewable Energy Insurance
- › Farm Insurance
Insurance by Industry
Shopping Centre Insurance
Shopping centre insurance for strip centres, retail parks and enclosed centres: car park and common area liability, the building, rent roll, glass and lifts.
Shopping centre insurance is for the owners of strip centres, neighbourhood centres and retail parks, where shoppers and tenants share the same car park and walkways. Your lender will expect the building insured with its interest noted, and the leases decide how much of the premium can be recovered from tenants as outgoings. Fortis Risk Solutions compares wordings across insurers, checks that the liability limit suits the foot traffic and makes sure lifts, escalators and glass are not left out. We set the rent roll section from the current leases and can suggest what cover to require from tenants. Have the tenancy schedule ready. Call 03 7046 3766 or send an enquiry.
What Shopping Centre Insurance Covers
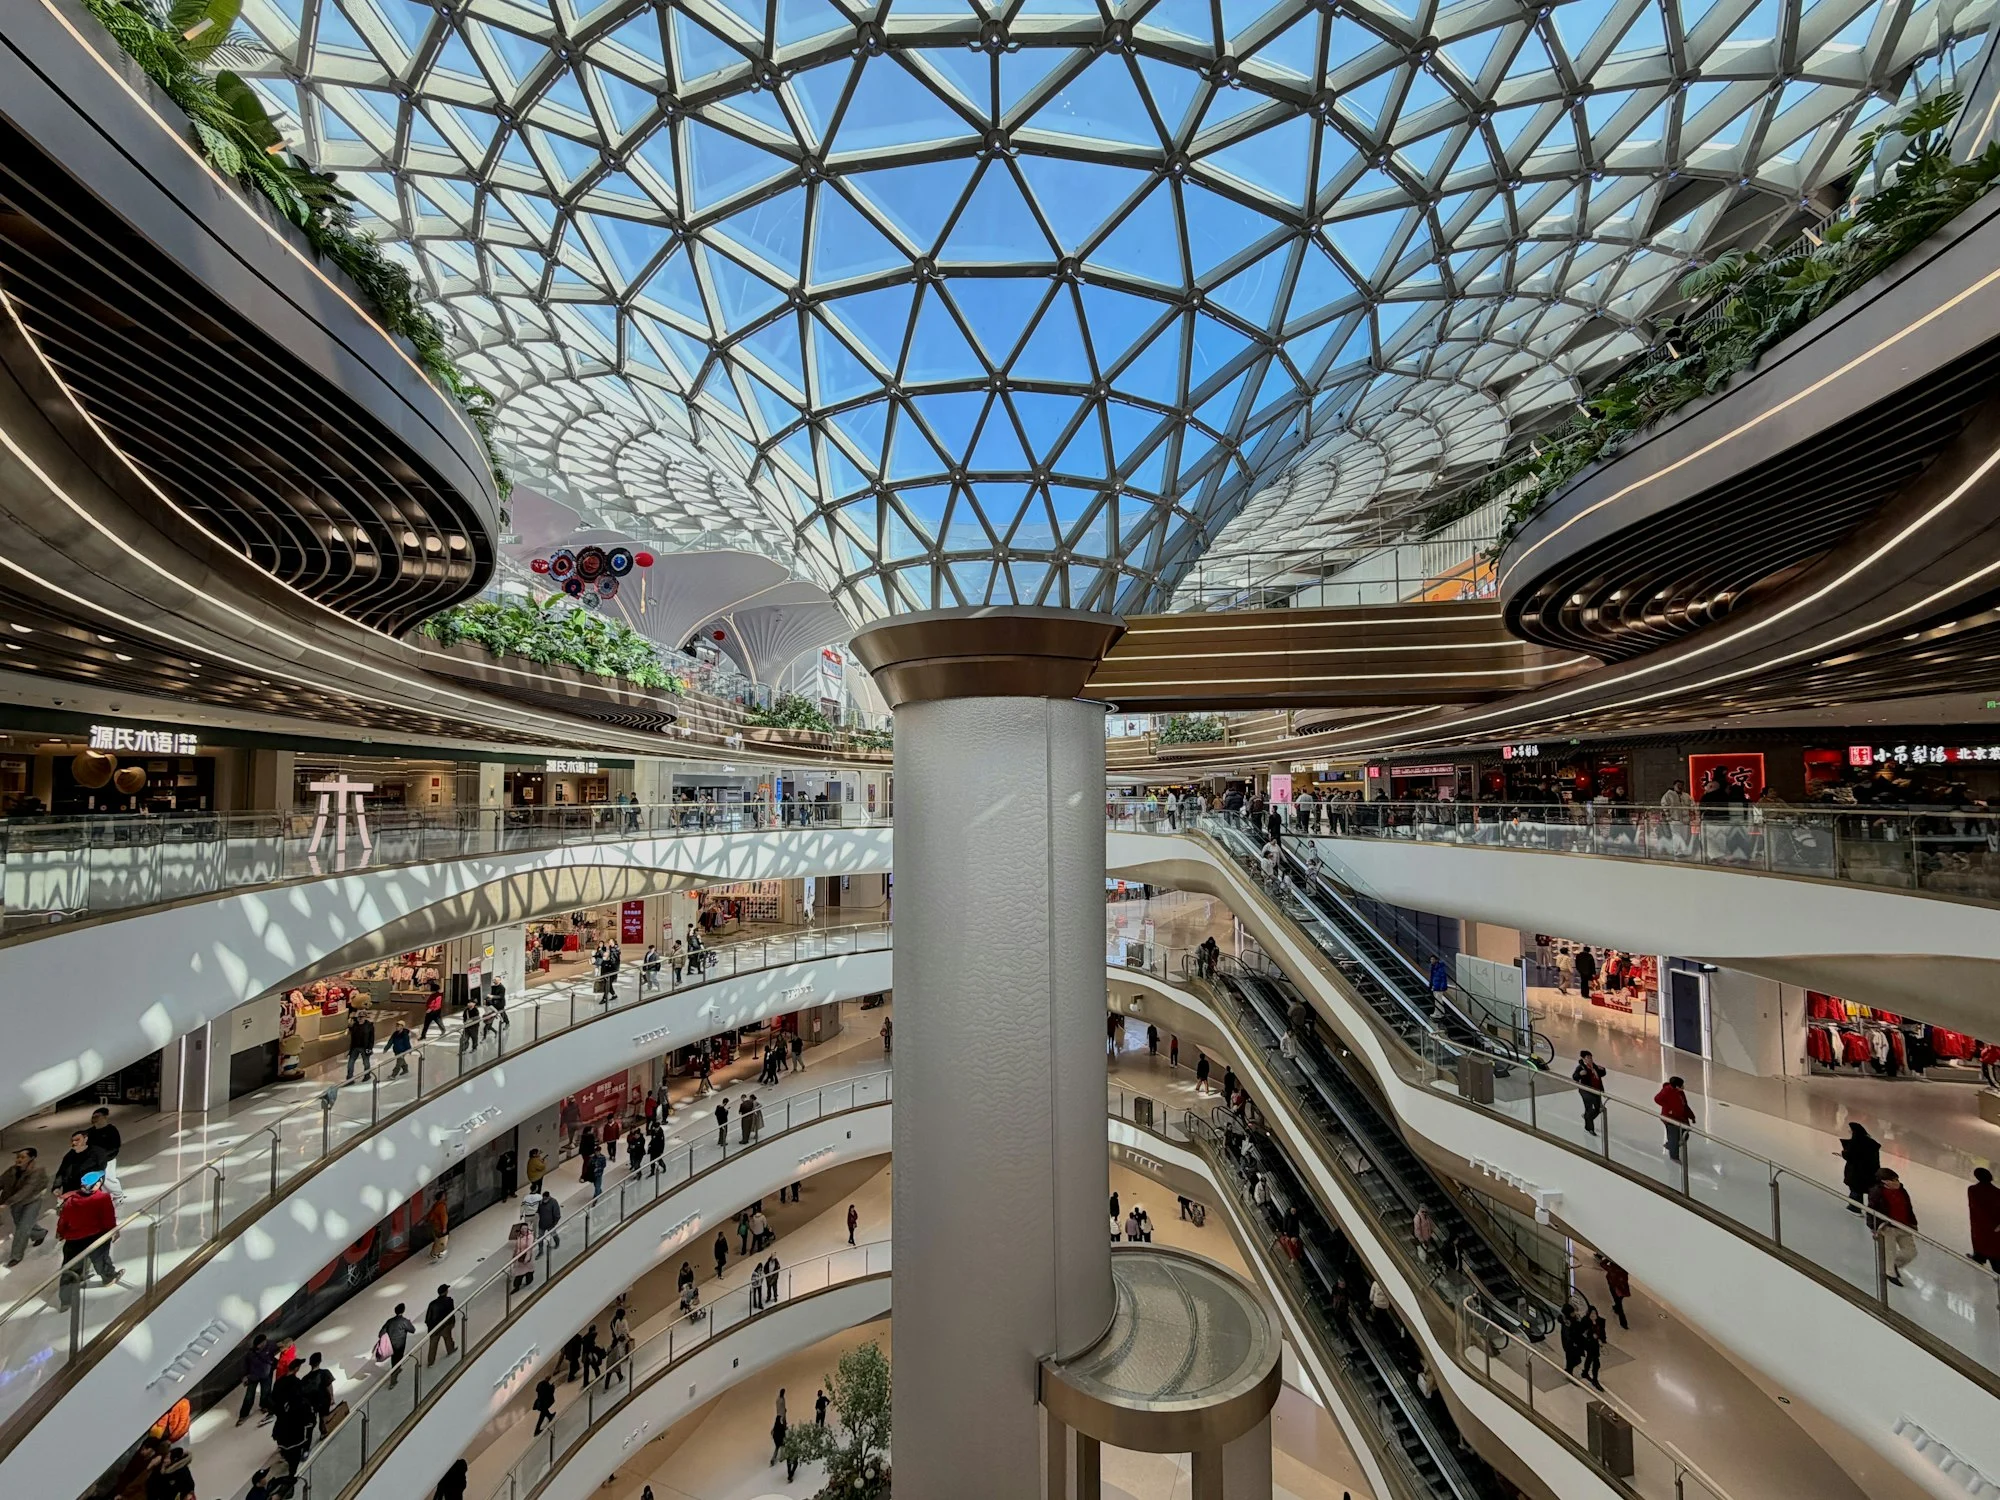
Shopping centre insurance covers the building, the car park and common areas, the rent roll and the owner's legal liability for neighbourhood centres, strip shopping centres, retail parks and larger enclosed centres. The policy is written around a building the public walks through every day, with many tenants paying rent under it, rather than around a single shop.
The risks come from the public and from the plant. A shopper slips on a spilt drink in the food court. A car reverses into a pedestrian in the car park, or a loose trolley rolls into a parked car. An escalator stops with a motor fault. A storm sends water through a skylight into three tenancies, and their rent abates while the shops are repaired.
Shopping centre liability insurance is the section most owners think of first. The limit of public liability insurance for a centre is usually set well above that of a single shop. In Victoria, retail leases fall under the Retail Leases Act 2003, and the lease decides which outgoings, insurance premiums included, the tenants share. Owners must also maintain essential safety measures such as fire services and exit lighting.
Fortis Risk Solutions arranges shopping centre insurance from offices in Box Hill and Hawthorn as part of our business insurance range. Whether you call it shopping mall insurance or retail centre insurance, we start with the rent roll, the tenancy mix, the car park and the lifts. Smaller centres usually sit under commercial property insurance. Larger ones move to an industrial special risks wording.
Who this covers
Businesses in this group include:
- Neighbourhood and strip shopping centres
- Larger shopping centres
- Retail parks and bulky goods centres
- Mixed use retail and office buildings
- Centre managers
If your business is not listed, ask us. The sections below are the starting point for any business in the group.
Shopping Centre Insurance: Cover Sections and Benefits
Related Client Case Studies
Cases from the Fortis Risk Solutions broking team. Client names have been removed.
Client case: Property Damage, Stock and Business Interruption After a Cyclone
The client situation: A restaurant located inside a shopping centre was forced to temporarily close after a cyclone in Queensland caused a prolonged power outage to the centre. The loss of electricity caused refrigerated and frozen food stock to spoil and prevented the restaurant from trading.
The incident happened just 6 weeks after the restaurant opened. We had provided holistic risk advice prior to the opening, and they had taken the necessary insurance to protect their operation.How the policy responded: Its Business Insurance policy included cover for Business Interruption arising from damage and loss of stock from storm damage affecting utility services, allowing the cyclone-related power outage and the resulting loss of income and gross profit to be recovered under the policy.
The restaurant claimed approximately $2,368 for spoiled stock and subsequently $1,384 a week of lost Gross Profit for 13 weeks until they fully recovered from the cyclone, a total indemnity of $23,989 including cleaning costs and other additional increased costs of working.How Fortis Risk Solutions helps: We advise on risk before a venue opens, not after the first loss. Utility failure and stock spoilage were on this policy because we raised them at the start.
Client case: Success Story: Commercial Strata Renewal
The client situation: A commercial strata property, 1 km from the Melbourne CBD, with a building sum insured close to the $10 million mark. We were approached by the property owner after they received a premium increase of nearly 25% on their renewal terms.
How we handled the case: By talking with the owner and the property manager, through a thorough know your client (KYC) and needs analysis process, we found that the occupations of 3 of the 9 commercial tenants had not been updated with the holding insurer. This caused an unnecessary premium increase and limited the insurer options.
We prepared detailed client file notes, obtained the most up to date and accurate information, approached more than 15 insurers and underwriters, and negotiated renewal terms on the insured’s behalf after obtaining a Letter of Authority to quote.Claim result: Instead of a significant premium increase, we secured renewal terms with broader coverage at a cost $8,985 less than the previous year.
How Fortis Risk Solutions helps: A renewal notice is not the only offer available. We check that the insurer holds the right information and take the risk to the wider market.
Every policy is different and the outcome of a claim depends on its terms. As your broker, Fortis Risk Solutions compares insurers and policy wording before you buy, and lodges and manages the claim for you when something happens. Talk to us about your own cover.
Shopping Centre Insurance FAQs
It covers the owner's legal liability for injury to shoppers, tenants' staff and visitors, and for damage to their property, in the common areas, car parks and access roads the owner controls. It pays compensation and legal defence costs. Slips in food courts, trips on car park kerbs and falling objects are typical claims. Leases usually require tenants to hold their own liability cover for their shops.
Usually once the building and rent values grow past what a standard commercial wording is built for. ISR insurance is written on an all risks basis and covers material damage and loss of rent together for the whole site. The point at which a centre moves across differs between insurers. Smaller strip centres can stay under commercial building insurance, so we compare both forms.
Yes, when the tenancy cannot be used because of insured damage and the policy includes a loss of rent section. Most retail leases suspend or reduce rent while a shop is unusable. The policy pays the rent you would have collected for the indemnity period. It does for an owner what business interruption insurance does for a trading business.
Damage from fire or impact is covered by the building section, but a mechanical or electrical failure inside a lift or escalator is not. That needs a machinery breakdown section, which pays for the repair and, where selected, the rent or extra cost while the plant is down. Insurers usually ask for the maintenance contract details before they offer it.
Usually, where the centre is owned through a company, trust or syndicate. Management liability insurance covers the directors and the owning entity for claims a property policy will not answer. Examples are employment disputes with centre staff, regulator investigations and some tax audit costs. A centre manager employed by the owner is part of that exposure.
Centre wordings differ on liability limits, rent abatement, sprinkler conditions, machinery breakdown and how the indemnity period is set. FRS helps you disclose the tenancy mix and site accurately, structure limits for the building, rent and liability, compare specialist property insurers and act as your advocate at claim time. Owners who also run a business from the centre can add a business insurance package for it.
Talk to a broker about Shopping Centre Insurance
Call 03 7046 3766 on weekdays between 9:30am and 6pm, email admin@fortisrisksolutions.com.au, or send an enquiry and a broker from our Box Hill or Hawthorn office will come back to you about shopping centre insurance. Tell us what the business does and what the lease or contract asks for, and we take it from there.