
Personal Insurance
Business Insurance
- Business Insurance
- Industrial Special Risks (ISR) Insurance
- Commercial Property Owner Insurance
- Business Interruption Insurance
- Public Liability Insurance
- Professional Indemnity Insurance
- Management Liability Insurance
- Contract Works/Construction Insurance
- Marine Insurance
- Cyber Insurance
- Commercial Motor Insurance
- Faith & Not-for-Profit Organisations Insurance
Industry
- Retail and Consumer Insurance
- › Retail Strip Shop Insurance
- › Asian Grocery Store and Supermarket Insurance
- Hospitality and Tourism Insurance
- › Restaurant Insurance
- › Cafe and Bakery Insurance
- › Hotel and Hospitality Property Insurance
- › Takeaway Shop Insurance
- › Pub and Bar Insurance
- › Short Term Rental Insurance
- Commercial and Industrial Property Insurance
- › Warehouse Property Insurance
- › Service Station and Convenience Store Insurance
- › Loss of Rent Insurance
- › Shopping Centre Insurance
- › Rooming House Insurance
- Construction and Trades Insurance
- › Architect and Design Insurance
- › Plumber and Electrician Insurance
- Property and Real Estate Insurance
- › Property and Real Estate Agency Insurance
- Manufacturing and Industrial
- › Food Manufacturing Insurance
- Trade and Logistics Insurance
- Professional Services Insurance
- › Financial Services Insurance
- Health and Care Services Insurance
- › NDIS Provider Insurance
- › Aged Care Insurance
- › Psychologist Insurance
- › Physio Insurance
- Events and Entertainment Insurance
- › Personal Trainer and Gym Insurance
- Transport and Automotive Insurance
- › Rideshare Insurance
- › Truck Insurance
- Community, Education and Public Sector Insurance
- › Childcare Centre and Kindergarten Insurance
- High Value and Complex Business Insurance
- › Renewable Energy Insurance
- › Farm Insurance
Insurance by Industry
- Retail and Consumer Insurance
- › Retail Strip Shop Insurance
- › Asian Grocery Store and Supermarket Insurance
- Hospitality and Tourism Insurance
- › Restaurant Insurance
- › Cafe and Bakery Insurance
- › Hotel and Hospitality Property Insurance
- › Takeaway Shop Insurance
- › Pub and Bar Insurance
- › Short Term Rental Insurance
- Commercial and Industrial Property Insurance
- › Warehouse Property Insurance
- › Service Station and Convenience Store Insurance
- › Loss of Rent Insurance
- › Shopping Centre Insurance
- › Rooming House Insurance
- Construction and Trades Insurance
- › Architect and Design Insurance
- › Plumber and Electrician Insurance
- Property and Real Estate Insurance
- › Property and Real Estate Agency Insurance
- Manufacturing and Industrial
- › Food Manufacturing Insurance
- Trade and Logistics Insurance
- Professional Services Insurance
- › Financial Services Insurance
- Health and Care Services Insurance
- › NDIS Provider Insurance
- › Aged Care Insurance
- › Psychologist Insurance
- › Physio Insurance
- Events and Entertainment Insurance
- › Personal Trainer and Gym Insurance
- Transport and Automotive Insurance
- › Rideshare Insurance
- › Truck Insurance
- Community, Education and Public Sector Insurance
- › Childcare Centre and Kindergarten Insurance
- High Value and Complex Business Insurance
- › Renewable Energy Insurance
- › Farm Insurance
Insurance by Industry
Food Manufacturing Insurance
Food manufacturing insurance for food and beverage producers, wholesale kitchens and suppliers: product recall, contamination, machinery breakdown, spoiled stock and product liability claims.
Food manufacturing insurance is aimed at businesses that make, pack or bottle product for someone else to sell, from a wholesale kitchen to a contract packer. Supermarket and wholesale buyers often write minimum product liability limits into supplier agreements, and some ask about recall cover before they range a new line. We focus on what a standard business pack tends to exclude or cap tightly: recall, contamination and stock spoiled after a refrigeration failure. Fortis Risk Solutions compares those wordings across insurers and explains the differences. When a batch goes wrong, we help you notify the insurer early and manage the claim. Have your food safety plan and supplier agreements handy. Call 03 7046 3766 or send an enquiry.
What Food Manufacturing Insurance Covers
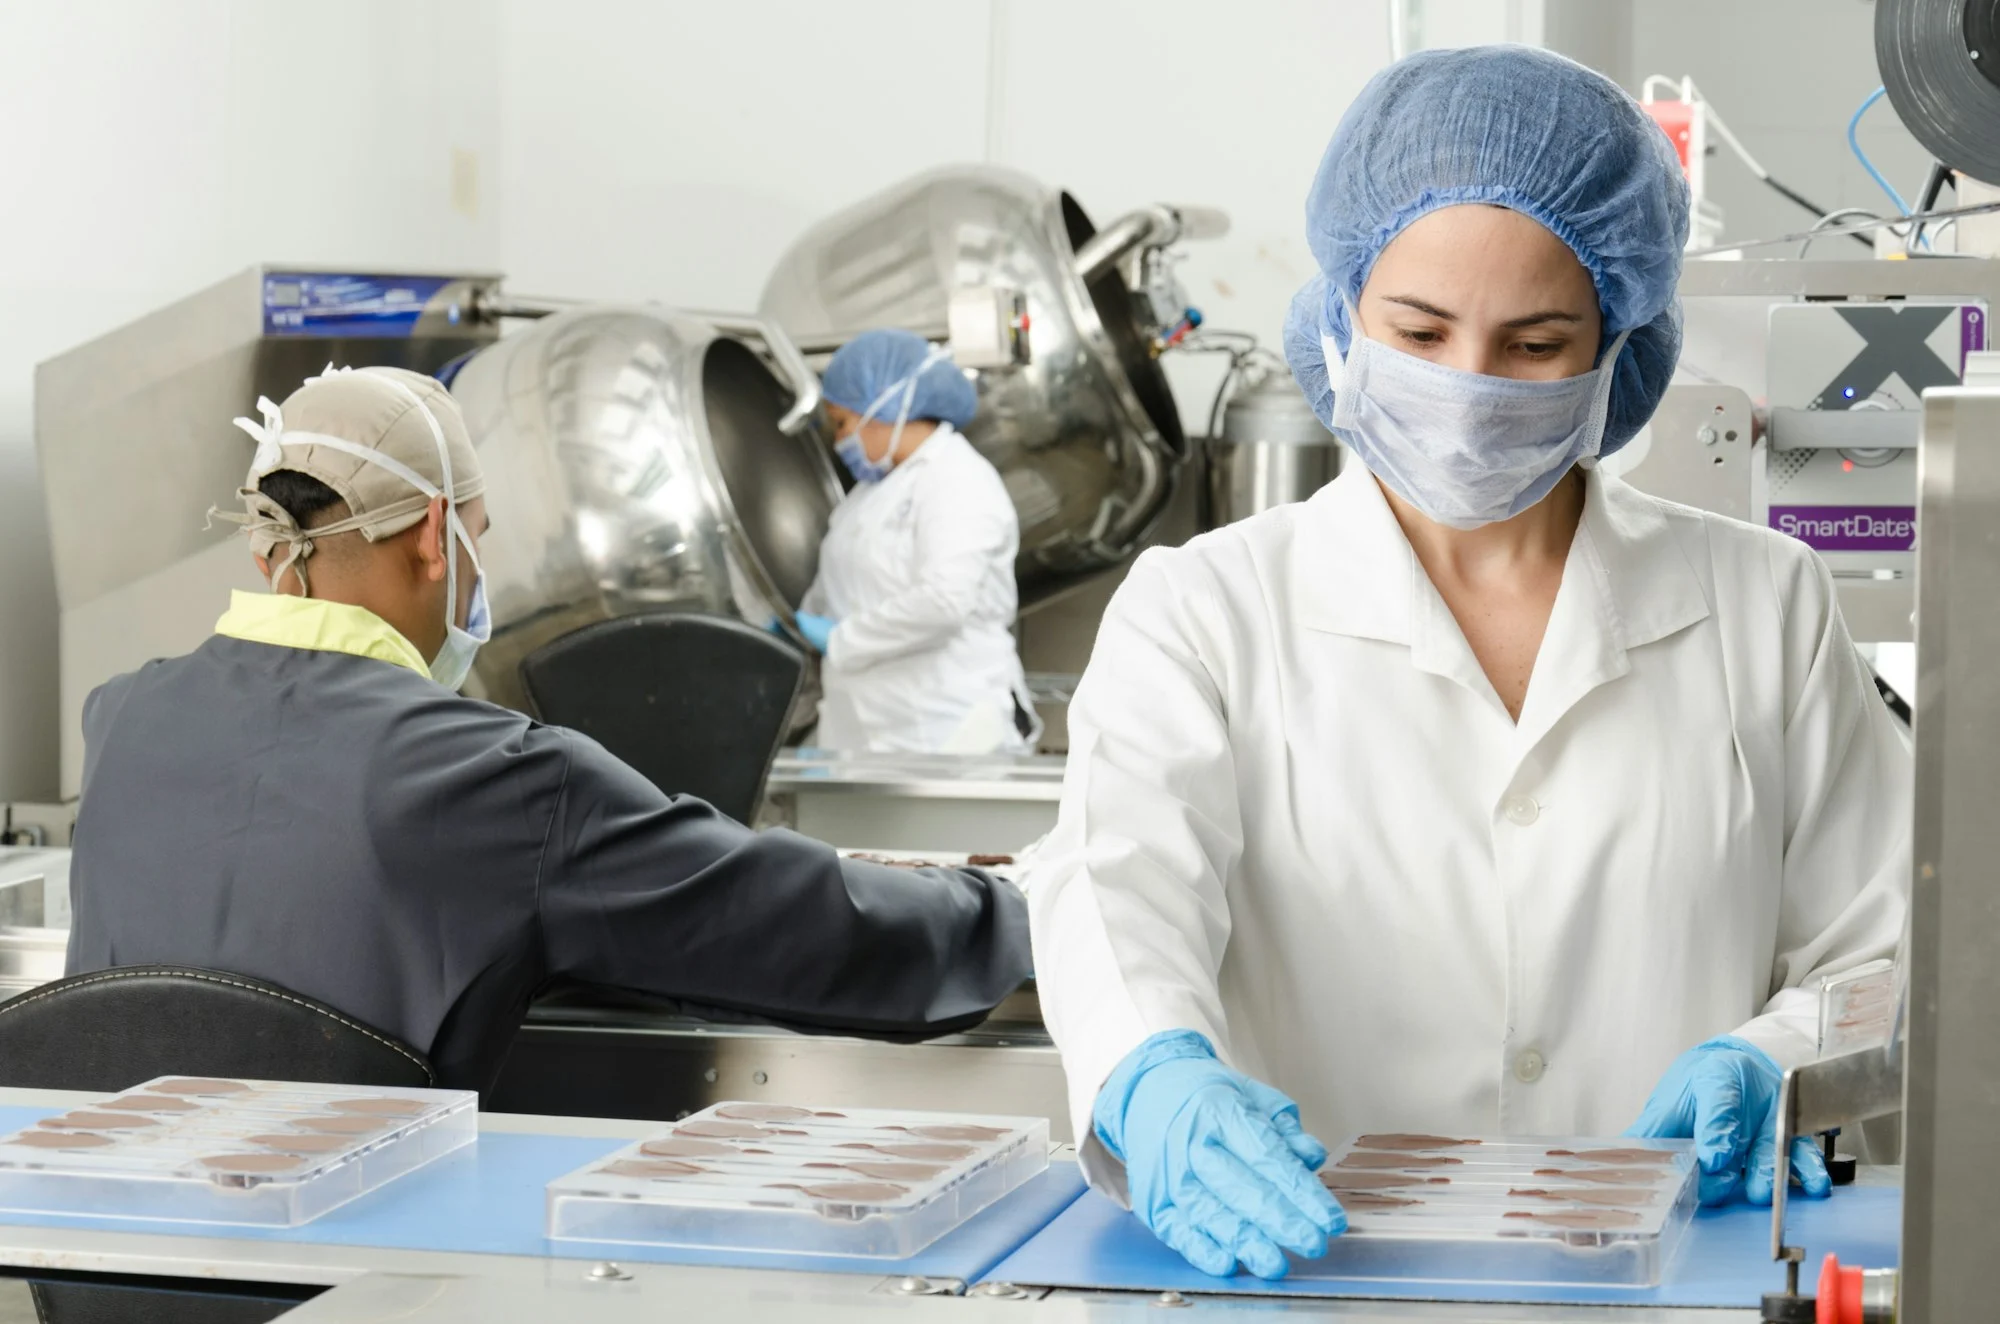
Food manufacturing insurance covers the plant, the stock, the product liability and the cost of a recall for businesses that make, pack or supply food and drink to other businesses. It suits a food production business of any size, from a commercial kitchen supplying cafes to a factory filling supermarket orders, because the risk follows the product after it leaves your door.
The losses are specific to food. A worn blade sheds metal into a batch. A label leaves out an allergen and the product has to come off the shelves. A blast freezer fails over a weekend and the stock is lost. A mixer or oven breaks down halfway through a contract run. A retailer then passes on the cost of the recall it had to manage.
The Food Standards Code requires allergens to be declared on the label, and Food Standards Australia New Zealand coordinates food recalls with the states. In Victoria, PrimeSafe licenses meat and seafood processors, and Dairy Food Safety Victoria licenses dairy businesses. Retail customers usually ask suppliers for proof of public liability insurance that includes products cover.
Fortis Risk Solutions arranges food processing insurance as part of our business insurance range from offices in Box Hill and Hawthorn. We look at the ingredients, the processes, the food safety program and who you sell to before approaching insurers. Factories outside food are covered on our manufacturing insurance page. Goods shipped interstate or overseas need cargo insurance while in transit.
Who this covers
Businesses in this group include:
- Food manufacturers and processors
- Commercial kitchens supplying wholesale
- Bakeries producing for wholesale
- Beverage producers: brewers, distillers, juice and soft drink makers
- Food wholesalers and suppliers
If your business is not listed, ask us. The sections below are the starting point for any business in the group.
Food Manufacturing Insurance: Cover Sections and Benefits
Related Client Case Studies
Cases from the Fortis Risk Solutions broking team. Client names have been removed.
Client case: Factory Fire: Property and Business Interruption
The client situation: A fire started in a manufacturing facility following an electrical fault, damaging production machinery, raw materials, finished goods, office contents and sections of the factory fit-out.
Production had to stop while the damaged area was repaired and replacement machinery was arranged.How the policy could respond: Property cover could assist with insured damage to machinery, stock, contents and fit-out.
Business Interruption cover could help with insured loss of income and applicable ongoing expenses while production was disrupted.
Additional increased costs incurred to maintain production may also be covered where provided by the policy.How Fortis Risk Solutions helps: We work out the indemnity period with the owner from the lead time on replacement machinery, which is often longer than the repair to the building.
Client case: Machinery Breakdown Stops Production
The client situation: A significant electrical event damaged sensitive electronic controls within several production machines. Several critical production machines suffered a sudden mechanical breakdown during operation. The affected machines could not operate until replacement components were sourced and installed.
Orders were delayed and sales declined during the interruption.How the policy could respond: Machinery Breakdown cover could assist with insured repair or replacement costs following a covered breakdown.
Appropriate Business Interruption or Consequential Loss following Machinery Breakdown cover could assist with insured loss of income resulting from the reduction in production.How Fortis Risk Solutions helps: Breakdown is not fire, and a standard property section does not cover it. We add machinery breakdown and the business interruption that follows it for any plant that depends on a few machines.
Client case: Refrigeration Failure and Spoiled Stock
The client situation: A refrigeration unit unexpectedly failed overnight. By the time staff arrived the next morning, a large quantity of frozen seafood, meat and other temperature-sensitive products had spoiled and could no longer be sold.
How the policy could respond: Machinery Breakdown could help with the insured repair costs for the refrigeration equipment.
Deterioration of Stock cover could help with the value of spoiled refrigerated and frozen goods.
If the breakdown significantly disrupted trading, applicable Business Interruption or Consequential Loss cover could assist with the resulting insured loss of income.How Fortis Risk Solutions helps: For a grocer the freezer is the business. We put machinery breakdown and deterioration of stock on the policy together, with a stock limit that matches a full cold room.
Every policy is different and the outcome of a claim depends on its terms. As your broker, Fortis Risk Solutions compares insurers and policy wording before you buy, and lodges and manages the claim for you when something happens. Talk to us about your own cover.
Food Manufacturing Insurance FAQs
Products liability and property cover are the base. Products liability answers claims that your food made someone ill or injured them, while property and machinery breakdown sections protect the factory and the line. Most manufacturers hold these in a business insurance package with deterioration of stock added, then consider product recall as a separate policy. Workers compensation is compulsory for most employers.
Not automatically. A standard liability policy pays injury and property damage claims but excludes the cost of recalling the product. Product recall cover is a separate section or policy that can pay for retrieving and destroying stock and notifying customers, and in some wordings for lost gross profit. It is usually triggered by accidental contamination or a labelling error.
Only with a deterioration of stock section. Property cover repairs the freezer or coolroom but does not replace what was inside it. Deterioration cover responds to breakdown of refrigeration plant and, depending on the wording, to a failure of the public power supply. The margin lost while production stops falls under business interruption insurance. Insurers often ask about temperature alarms on cold storage.
Most large retailers and distributors ask for a certificate of currency for public and products liability before they list a product, often at a set limit. Many also expect a recognised food safety certification. Read the supply agreement closely, because indemnity clauses can make you responsible for losses that a standard policy will not pay without the right wording.
Yes. Breweries, distilleries and juice or soft drink producers face the same contamination, recall and spoilage risks, plus glass breakage and pressure equipment. Producers that run a tasting room or cellar door take on visitor and liquor risks as well. That side of the business can be written under hospitality insurance alongside the production policy.
Recall, contamination and deterioration wordings differ sharply between insurers, and the gaps only show when a batch goes wrong. As your broker, FRS helps you disclose your products and processes accurately, structure liability and recall limits to match supply contracts, compare insurers that write food risks and act as your advocate at claim time. Tell us about a new major customer early, because one contract can change the limits you need.
Talk to a broker about Food Manufacturing Insurance
Call 03 7046 3766 on weekdays between 9:30am and 6pm, email admin@fortisrisksolutions.com.au, or send an enquiry and a broker from our Box Hill or Hawthorn office will come back to you about food manufacturing insurance. Tell us what the business does and what the lease or contract asks for, and we take it from there.