Personal Insurance
- Business Insurance
- Industrial Special Risks (ISR) Insurance
- Commercial Property Owner Insurance
- Business Interruption Insurance
- Public Liability Insurance
- Product Liability Insurance
- Professional Indemnity Insurance
- Management Liability Insurance
- Contract Works/Construction Insurance
- Cyber Insurance
- Commercial Motor Insurance
- Faith & Not-for-Profit Organisations Insurance
Industry
- Retail and Consumer Insurance
- › Retail Strip Shop Insurance
- › Asian Grocery Store and Supermarket Insurance
- › Grocery Store and Supermarket Insurance
- › Beauty Salon Insurance
- › Hair Salon and Barber Insurance
- › Massage Therapist Insurance
- › Wholesale and Distribution Insurance
- › Import and Export Insurance
- Hospitality and Tourism Insurance
- › Restaurant Insurance
- › Cafe and Bakery Insurance
- › Hotel and Hospitality Property Insurance
- › Takeaway Shop Insurance
- › Catering Insurance
- › Travel Agent and Tour Operator Insurance
- Commercial and Industrial Property Insurance
- › Warehouse Property Insurance
- › Service Station and Convenience Store Insurance
- › Shopping Centre Insurance
- › Childcare Property Insurance
- › Gym and Fitness Centre Insurance
- › Student Accommodation Insurance
- › Commercial Strata Insurance
- › Office Building Insurance
- › Holiday Park and Caravan Park Insurance
- › Farm Insurance
- › Data Centre Insurance
- › Cold Storage Insurance
- › Laboratory and Life Sciences Insurance
- Construction and Trades Insurance
- › Electrician Insurance
- › Plumbers Insurance
- › Solar Installer Insurance
- › Tradie Insurance
- › Commercial Builders Insurance
- › Domestic Builders Insurance
- Property and Real Estate Insurance
- Manufacturing and Industrial
- › Food Manufacturing Insurance
- › Plant and Machinery Insurance
- Trade and Logistics Insurance
- › Ecommerce Insurance
- Professional Services Insurance
- › Financial Services Insurance
- › Mortgage Broker Insurance
- › Accountants Insurance
- › Law Firm Insurance
- › IT Consultant Insurance
- › Engineers and Surveyors Insurance
- › Architect and Design Insurance
- › Property and Real Estate Agency Insurance
- › Media and Marketing Agency Insurance
- Health and Care Services Insurance
- › NDIS Provider Insurance
- › Aged Care Insurance
- › Psychologist Insurance
- › Physio Insurance
- › Counsellor Insurance
- › Medical Centre Insurance
- › Dental Practice Insurance
- Events and Entertainment Insurance
- › Go Kart Track Insurance
- Transport and Automotive Insurance
- › Mechanic Insurance
- › Fleet Insurance
- › Marine and Aviation Insurance
- › Car Dealership Insurance
- Community, Education and Public Sector Insurance
- › Childcare Centre and Kindergarten Insurance
- › Sports Club and Association Insurance
- › School and RTO Insurance
- High Value and Complex Business Insurance
- › Renewable Energy Insurance
- › Technology Company Insurance
- › EV Charging Insurance
- › Franchise Insurance
Insurance by Industry
- Retail and Consumer Insurance
- › Beauty Salon Insurance
- › Hair Salon and Barber Insurance
- › Massage Therapist Insurance
- › Wholesale and Distribution Insurance
- › Import and Export Insurance
- Hospitality and Tourism Insurance
- › Travel Agent and Tour Operator Insurance
- Commercial and Industrial Property Insurance
- › Data Centre Insurance
- › Cold Storage Insurance
- › Laboratory and Life Sciences Insurance
- Construction and Trades Insurance
- › Commercial Builders Insurance
- › Domestic Builders Insurance
- Property and Real Estate Insurance
- Manufacturing and Industrial
- › Plant and Machinery Insurance
- Trade and Logistics Insurance
- › Ecommerce Insurance
- Professional Services Insurance
- › Media and Marketing Agency Insurance
- Health and Care Services Insurance
- › Medical Centre Insurance
- › Dental Practice Insurance
- Events and Entertainment Insurance
- › Go Kart Track Insurance
- Transport and Automotive Insurance
- › Car Dealership Insurance
- Community, Education and Public Sector Insurance
- › Sports Club and Association Insurance
- › School and RTO Insurance
- High Value and Complex Business Insurance
- › EV Charging Insurance
- › Franchise Insurance
Insurance by Industry
Commercial Builders Insurance
Commercial builders insurance for Melbourne contractors: contract works, public liability, plant and equipment, and professional indemnity for design and construct, checked against what your head contract requires.
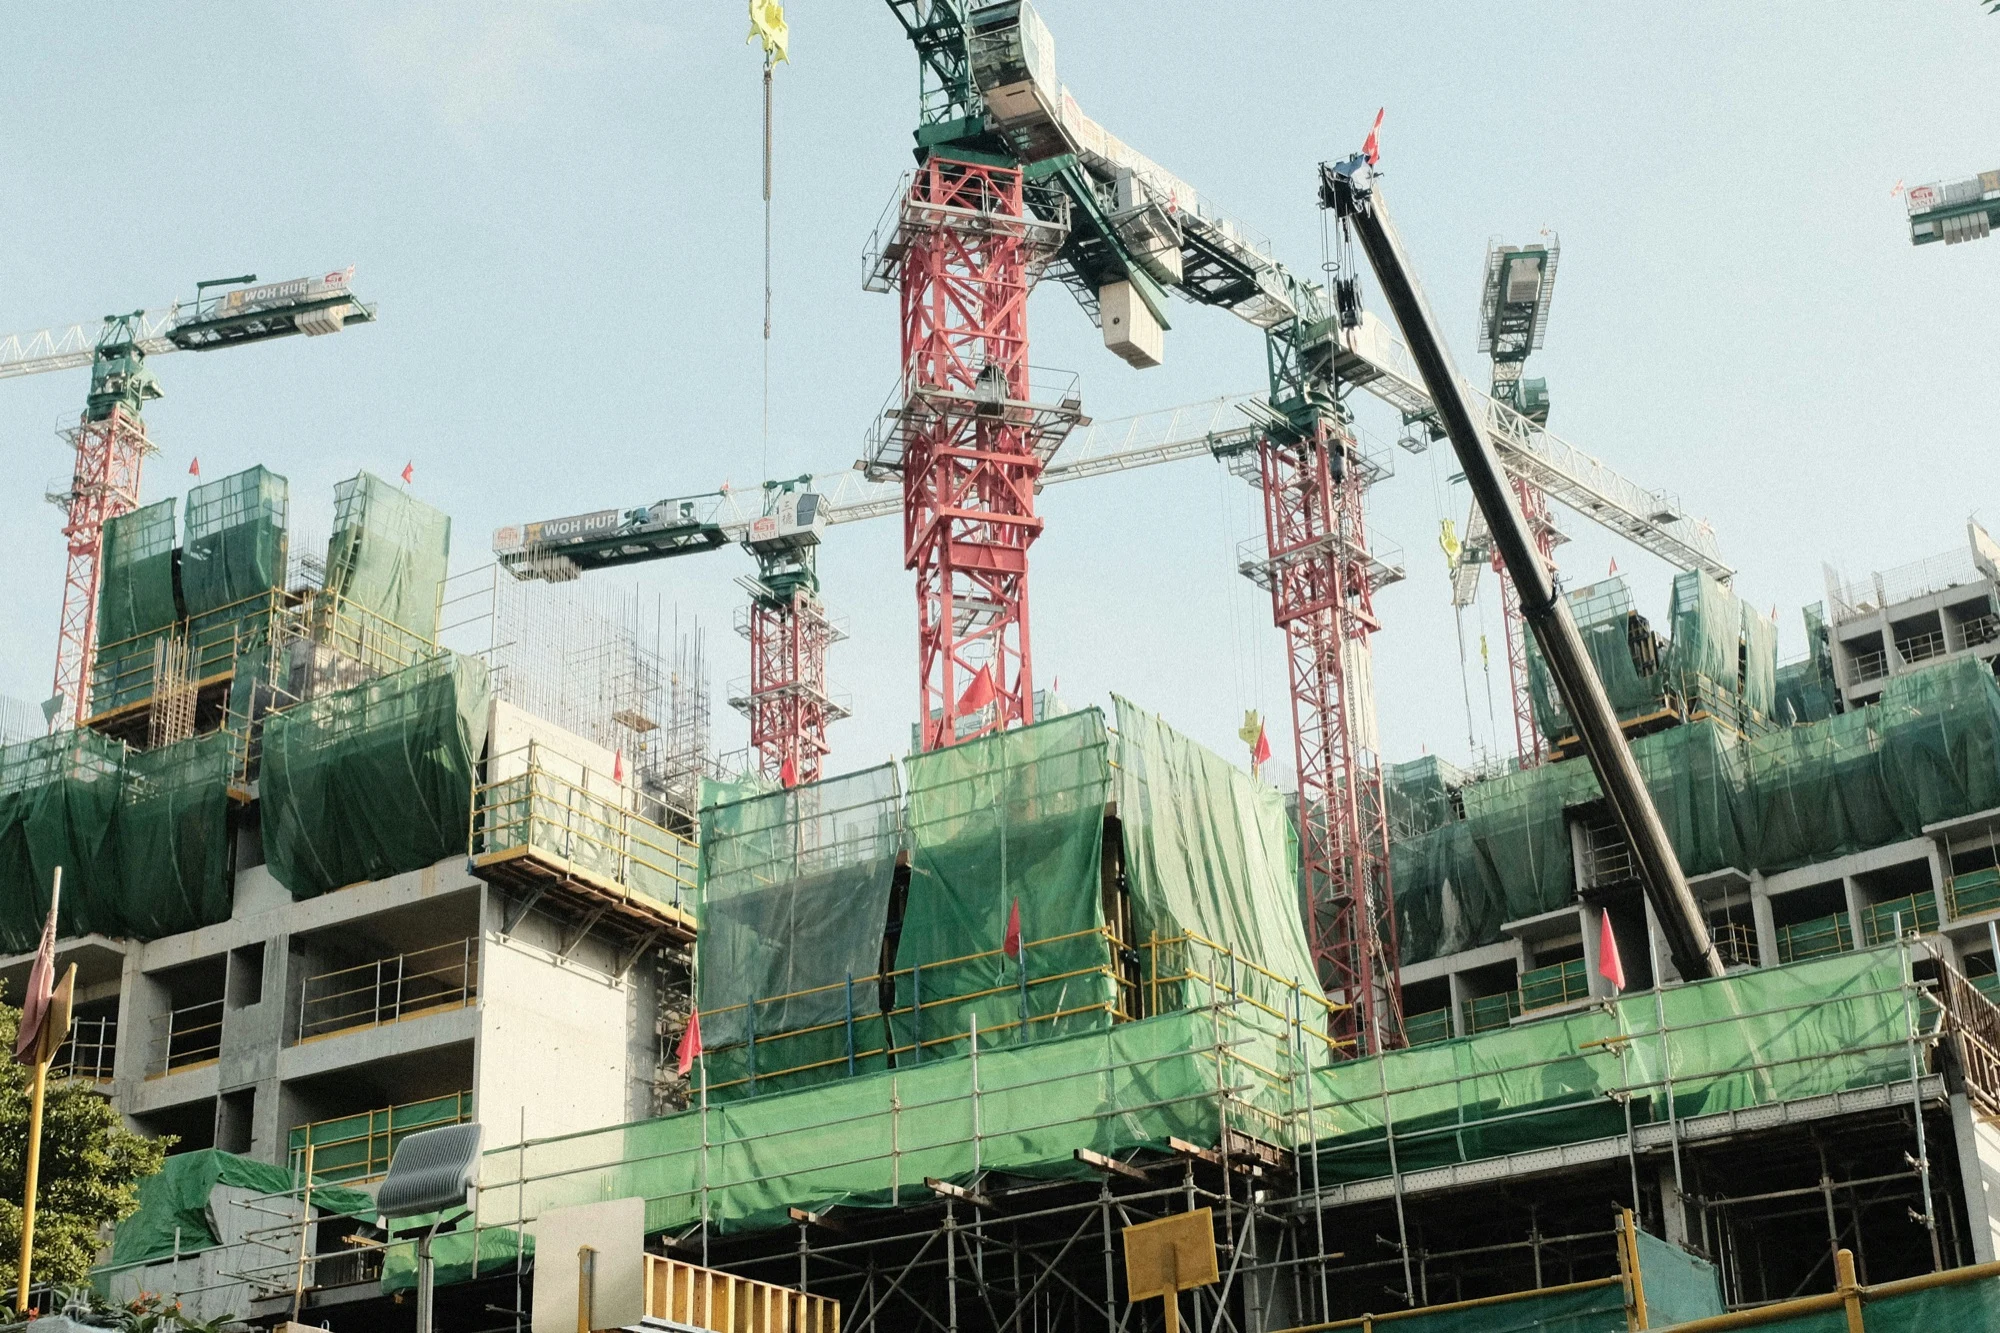
Commercial builders insurance is for builders, fit-out contractors and developers working on offices, warehouses, shops and apartment buildings. It covers the works until handover, the public and neighbours around the site, plant and tools, and design errors on design and construct jobs, matched to what your head contract requires. Fortis Risk Solutions arranges it from offices in Box Hill and Hawthorn. Call 03 7046 3766 or send an enquiry.
What Commercial Builders Insurance Covers
Commercial construction insurance covers the risks a builder carries on offices, warehouses, shop fit-outs, apartment buildings and other non-residential projects: damage to the works while they are being built, injury to the public and damage to neighbouring property, loss of plant and tools, and design errors where the builder takes on design. Most of it is driven by the head contract, which sets out who insures what and on what terms.
Contract works insurance covers the project itself against fire, storm, theft, vandalism and accidental damage until handover. It can be bought for a single project or as an annual policy that picks up every job under a set contract value. Some principals insure the works themselves under a principal-arranged policy, so read the contract before you buy, and confirm whether you and your subcontractors are insured under it.
Public liability is the other cover every head contract asks about. A load swinging over a footpath, dust through a neighbour's air conditioning or a cut service cable can all become claims against the builder. Principals usually ask for a minimum limit, for their name to be noted on the policy and for a certificate of currency before you start on site. Damage from vibration or removal of support is often excluded unless added, which matters on basement and excavation jobs.
Fortis Risk Solutions arranges commercial builders insurance from offices in Box Hill and Hawthorn, and our team can explain it in Mandarin. We work with commercial builders, fit-out contractors and developers who build their own projects. Commercial builders sit within our construction and trades insurance work.
Who this covers
Businesses in this group include:
- Commercial builders and construction managers
- Office, retail and hospitality fit-out contractors
- Industrial and warehouse builders
- Builders of apartment and mixed-use buildings
- Developers who build their own projects
- Specialist subcontractors working under head contracts
If your business is not listed, ask us. The sections below are the starting point for any commercial builder in the group.
Commercial Builders Insurance: Cover Sections and Benefits
- Contract works for the project until practical completion
- Annual contract works cover for multiple projects
- Existing structures during renovation and fit-out work
- Debris removal and professional fees after a loss
- Public liability with principals noted on the policy
- Vibration and removal of support, where added
Commercial Builders Insurance FAQs
The head contract decides who arranges contract works insurance. Some contracts require the builder to insure the works in the joint names of builder and principal, others have the principal take out the policy and the builder relies on it. Read the insurance clause before pricing the job, because the contract may make you responsible for the excess on the principal's policy.
It varies with the project and the principal. Large commercial and government work tends to ask for higher limits than a small fit-out, and many contracts also want the principal noted on your policy. Send us the insurance schedule from the contract and we will check your cover against it before you sign.
Usually, yes. Under a design and construct contract the builder takes responsibility for the design, even when consultants prepare the drawings. If a design fault appears after completion, contract works and public liability will not pay to correct the design itself. Professional indemnity covers claims for that kind of error, and principals often ask for it to stay in place for a period after the job.
Not usually. Contract works covers the project, and plant is normally excluded or limited. Owned plant needs its own policy, and hire agreements often make you responsible for hired-in plant while it is on your site, including hire charges that keep running after it is damaged. Large cranes are often insured by their owner, so check the hire terms.
The principal and the public will usually look to you first as head contractor. Before anyone starts, ask each subcontractor for a current certificate of currency for public liability and, where they employ staff, check their WorkCover. Your own policy may have conditions about subcontractors, and a gap in their cover can end up as a claim on yours.
Head contracts set out insurance requirements in detail, and missing one can delay site access or a progress payment. FRS reads the insurance clauses with you, matches limits and noted parties to each contract, compares insurers that write construction risks and acts as your advocate at claim time.
Talk to a broker about Commercial Builders Insurance
Call 03 7046 3766 on weekdays between 9:30am and 6pm, email admin@fortisrisksolutions.com.au, or send an enquiry and a broker from our Box Hill or Hawthorn office will come back to you about commercial builders insurance. Tell us what the business does and what the lease or contract asks for, and we take it from there.