
Personal Insurance
Business Insurance
- Business Insurance
- Industrial Special Risks (ISR) Insurance
- Commercial Property Owner Insurance
- Business Interruption Insurance
- Public Liability Insurance
- Product Liability Insurance
- Professional Indemnity Insurance
- Management Liability Insurance
- Contract Works/Construction Insurance
- Marine Insurance
- Cyber Insurance
- Commercial Motor Insurance
- Faith & Not-for-Profit Organisations Insurance
Industry
- Retail and Consumer Insurance
- › Retail Strip Shop Insurance
- › Asian Grocery Store and Supermarket Insurance
- › Bottle Shop Insurance
- Hospitality and Tourism Insurance
- › Restaurant Insurance
- › Cafe and Bakery Insurance
- › Hotel and Hospitality Property Insurance
- › Takeaway Shop Insurance
- › Pub and Bar Insurance
- › Catering Insurance
- Commercial and Industrial Property Insurance
- › Warehouse Property Insurance
- › Service Station and Convenience Store Insurance
- › Loss of Rent Insurance
- › Shopping Centre Insurance
- › Rooming House Insurance
- › Childcare Property Insurance
- Construction and Trades Insurance
- › Architect and Design Insurance
- › Electrician Insurance
- › Plumbers Insurance
- › Solar Installer Insurance
- › Tradie Insurance
- Property and Real Estate Insurance
- › Property and Real Estate Agency Insurance
- Manufacturing and Industrial
- › Food Manufacturing Insurance
- Trade and Logistics Insurance
- Professional Services Insurance
- › Financial Services Insurance
- Health and Care Services Insurance
- › NDIS Provider Insurance
- › Aged Care Insurance
- › Psychologist Insurance
- › Physio Insurance
- › Counsellor Insurance
- Events and Entertainment Insurance
- › Gym and Fitness Studio Insurance
- › Personal Trainer Insurance
- Transport and Automotive Insurance
- › Truck Insurance
- › Mechanic Insurance
- Community, Education and Public Sector Insurance
- › Childcare Centre and Kindergarten Insurance
- High Value and Complex Business Insurance
- › Renewable Energy Insurance
- › Farm Insurance
Insurance by Industry
- Retail and Consumer Insurance
- › Bottle Shop Insurance
- Hospitality and Tourism Insurance
- › Catering Insurance
- Commercial and Industrial Property Insurance
- Construction and Trades Insurance
- › Plumbers Insurance
- › Solar Installer Insurance
- › Tradie Insurance
- Property and Real Estate Insurance
- Manufacturing and Industrial
- Trade and Logistics Insurance
- Professional Services Insurance
- Health and Care Services Insurance
- › Counsellor Insurance
- Events and Entertainment Insurance
- › Personal Trainer Insurance
- Transport and Automotive Insurance
- › Mechanic Insurance
- Community, Education and Public Sector Insurance
- High Value and Complex Business Insurance
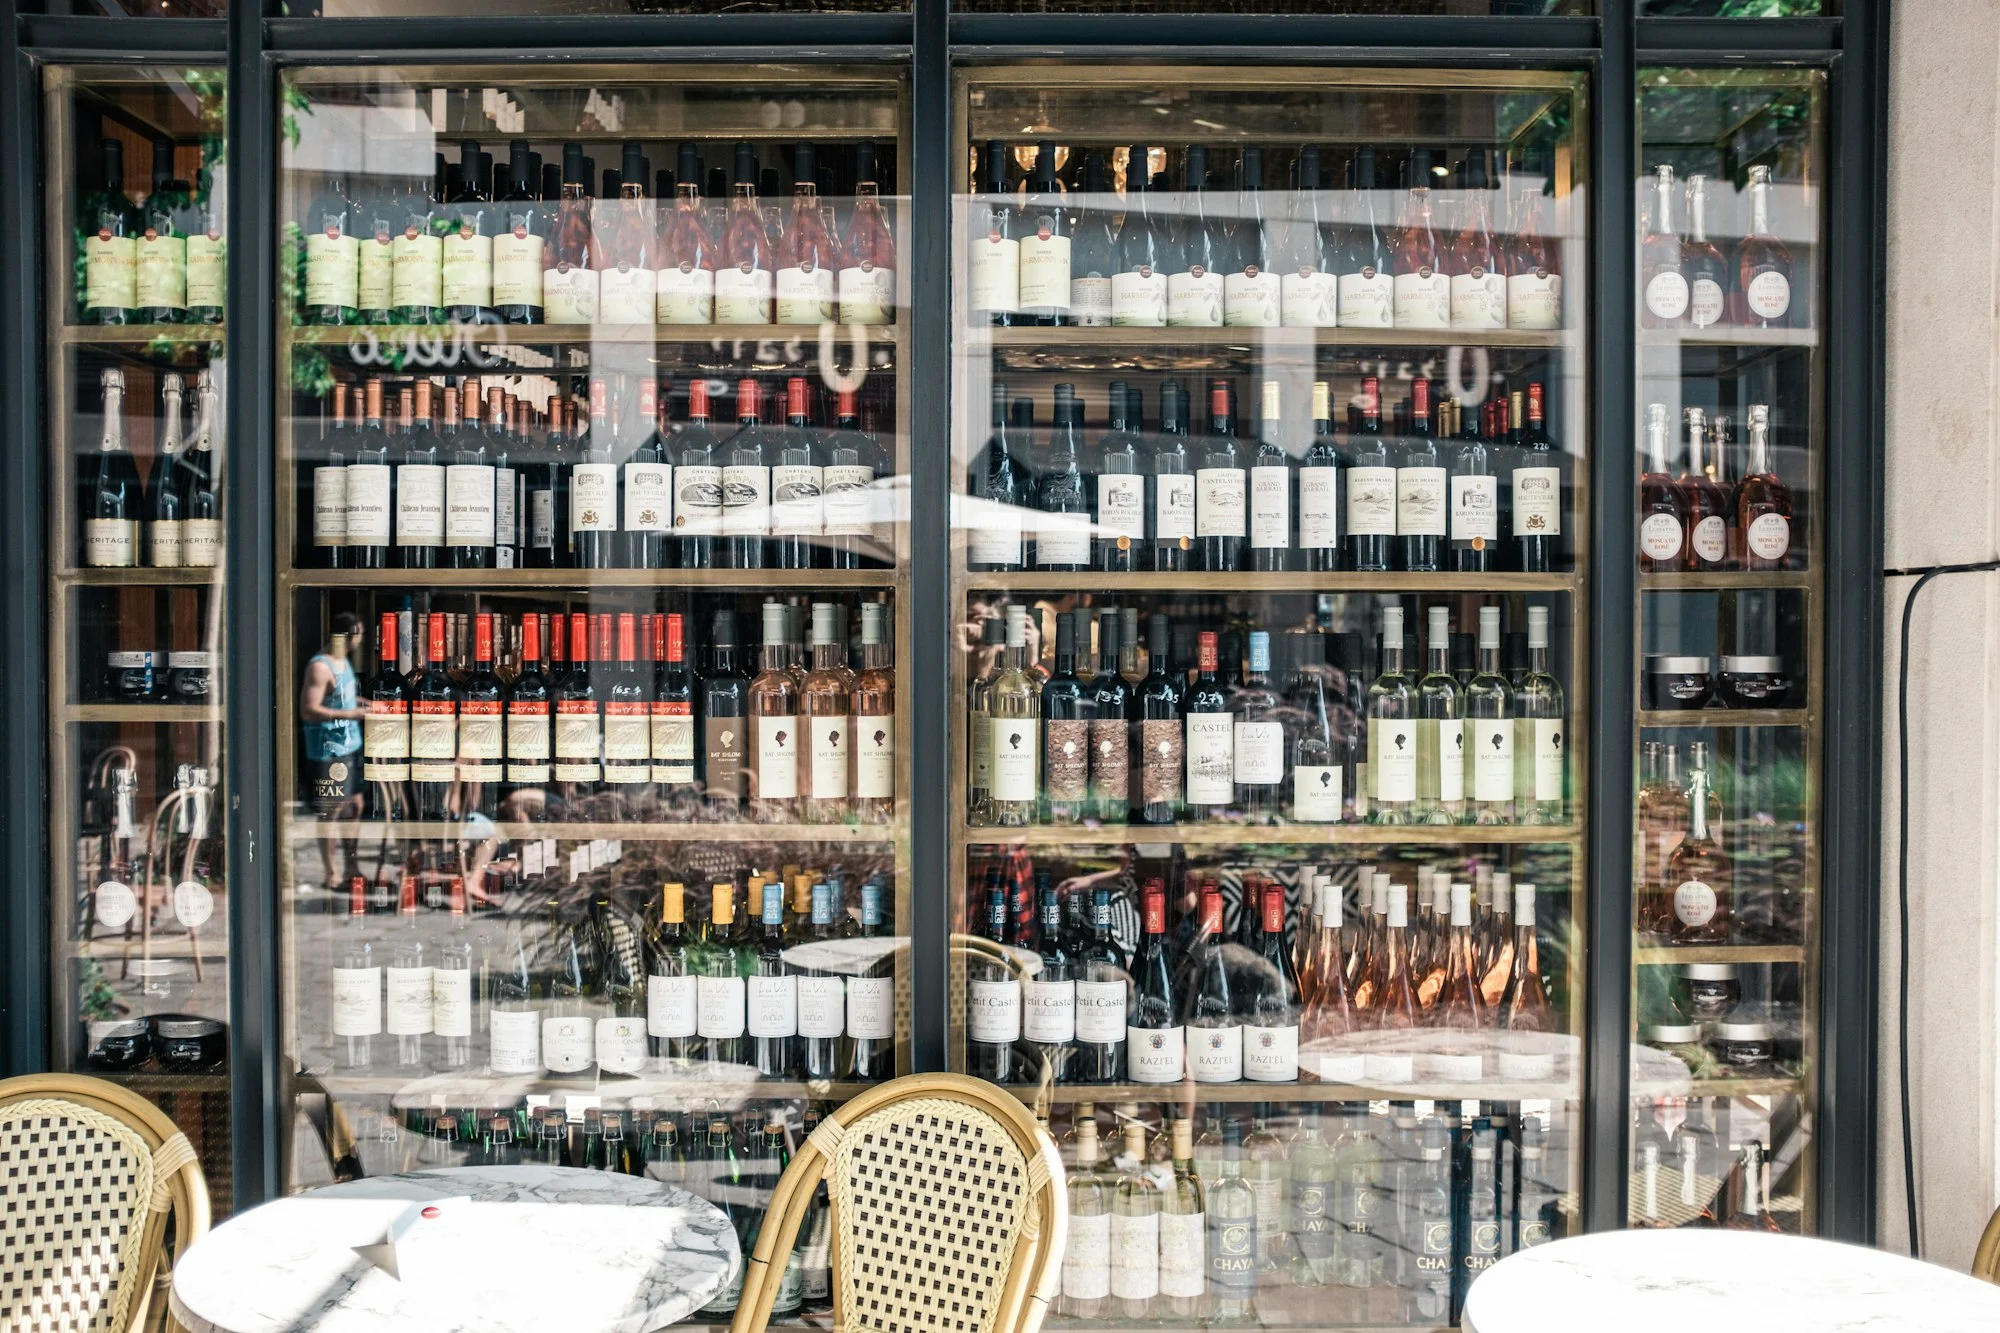
Insurance by Industry
Bottle Shop Insurance
Bottle shop insurance for owner-run bottle shops and liquor stores: stock theft and burglary, glass, cash, cool room breakdown and public liability.
Bottle shop insurance protects owner-run bottle shops and liquor stores against the losses that close a shop: break-ins and stock theft, smashed glass, lost cash, a failed cool room and claims from customers hurt on the premises. Fortis Risk Solutions arranges it from offices in Box Hill and Hawthorn. We look at your security, peak stock levels and cash handling first, then compare insurers that write liquor retailing.
What Bottle Shop Insurance Covers
Bottle shop insurance covers stock, glass, cash, cool rooms and public liability for owner-run bottle shops. Some owners search for liquor store insurance; the cover is the same. Liquor is worth a lot for its size and easy to resell, so insurers look hard at theft and break-in risk. A smashed display or a failed cool room compressor can also stop trade on a busy weekend.
In Victoria, a packaged liquor licence lets you sell alcohol in sealed containers for drinking off the premises. Liquor Control Victoria expects staff who sell alcohol to hold a Responsible Service of Alcohol certificate, and the refresher course is due every three years. Insurers ask about the licence when they quote, so keep it current and keep the RSA records on file.
Stock is usually the largest sum insured. Set it for the peak, not the average: the weeks before Christmas and long weekends carry far more than a quiet July. Landlords usually want public liability insurance in place before the lease starts. If a fire or burst pipe closes the shop, business interruption insurance is designed to replace the gross profit lost while you rebuild.
Fortis Risk Solutions arranges bottle shop insurance from offices in Box Hill and Hawthorn as part of our business insurance range. We go through security, stock levels, cash handling and the cool room before approaching insurers. We also check that your alarm and monitoring match what the policy will require. A shop that also sells groceries, tobacco or takeaway food may sit better under a wider retail strip shop insurance package.
Who this covers
Shops in this group include:
- Owner-run bottle shops and liquor stores
- Wine shops and craft beer specialists
- Spirits and whisky retailers
- Drive-through bottle shops
- Bottle shops in shopping strips and neighbourhood centres
If your shop is not listed, ask us. The sections below are the starting point for any shop selling packaged liquor.
Bottle Shop Insurance: Cover Sections and Benefits
Bottle Shop Insurance FAQs
Start with public and products liability, since you sell a product people consume and the landlord will want the certificate. Liquor store liability insurance, in practice, is that section. Then build a business insurance package around stock, glass, money, the fit-out and the cool room, with business interruption added.
It can be, under the theft section of a business pack, which usually needs forced and violent entry. Insurers set conditions on alarms, deadlocks and sometimes roller shutters or bollards. If those conditions are not met, a claim can be reduced or refused. Check whether the policy sets a lower theft limit for high value lines such as spirits.
A machinery breakdown section can pay to repair the compressor and refrigeration plant, depending on the policy wording. If you also hold perishables such as cheese, deli lines or ice, add deterioration of stock. Our guide to fridge breakdown and spoiled stock explains how insurers treat a power outage compared with a breakdown in your own equipment.
Enough for the largest amount of cash you actually hold, including weekend takings waiting for the bank. Policies set separate limits for cash during trading hours, cash in a locked safe and cash in transit. Insurers also set conditions on safe type and banking frequency, so tell us how and when you bank before the policy is placed.
Then the risk is closer to a pub or bar and needs a different licence and different cover. A packaged liquor licence only covers alcohol in sealed containers taken away. If you run a bar alongside the bottle shop, tell the insurer, and look at pub and bar insurance for the on-premises side, where liquor liability is a bigger question.
Liquor retailing wordings turn on security conditions, theft limits, cash limits and how stock is valued. FRS helps you disclose the trade accurately, structure sums insured for peak stock, compare insurers who write liquor retailing and act as your advocate at claim time. If you own more than one shop, we can place them together on one retail insurance program.
Talk to a broker about Bottle Shop Insurance
Call 03 7046 3766 on weekdays between 9:30am and 6pm, email admin@fortisrisksolutions.com.au, or send an enquiry and a broker from our Box Hill or Hawthorn office will come back to you about bottle shop insurance. Tell us what the business does and what the lease or contract asks for, and we take it from there.